Environmental Audits · Municipal Corporations
Environmental Audits for Municipal Corporations
For a municipal corporation, an environmental audit is the instrument that converts a completed civic programme into evidence an officer can produce when it is questioned.
Screening view on your project, with the category and route named. No obligation.
What this means for municipal corporations
Civic environmental spending is unusually exposed: it is a public tender, a public asset and a public claim, and all three are open to RTI, to the chief auditor, to the standing committee and to a Tribunal application by a resident. The question asked is never whether the work was sanctioned but whether it performed: whether the STP met its consent conditions, whether the processing facility handled the tonnage it was paid for, whether the trees planted three years ago are alive. An audit answers that with measurement, or it is not an audit.
How KIPL runs it
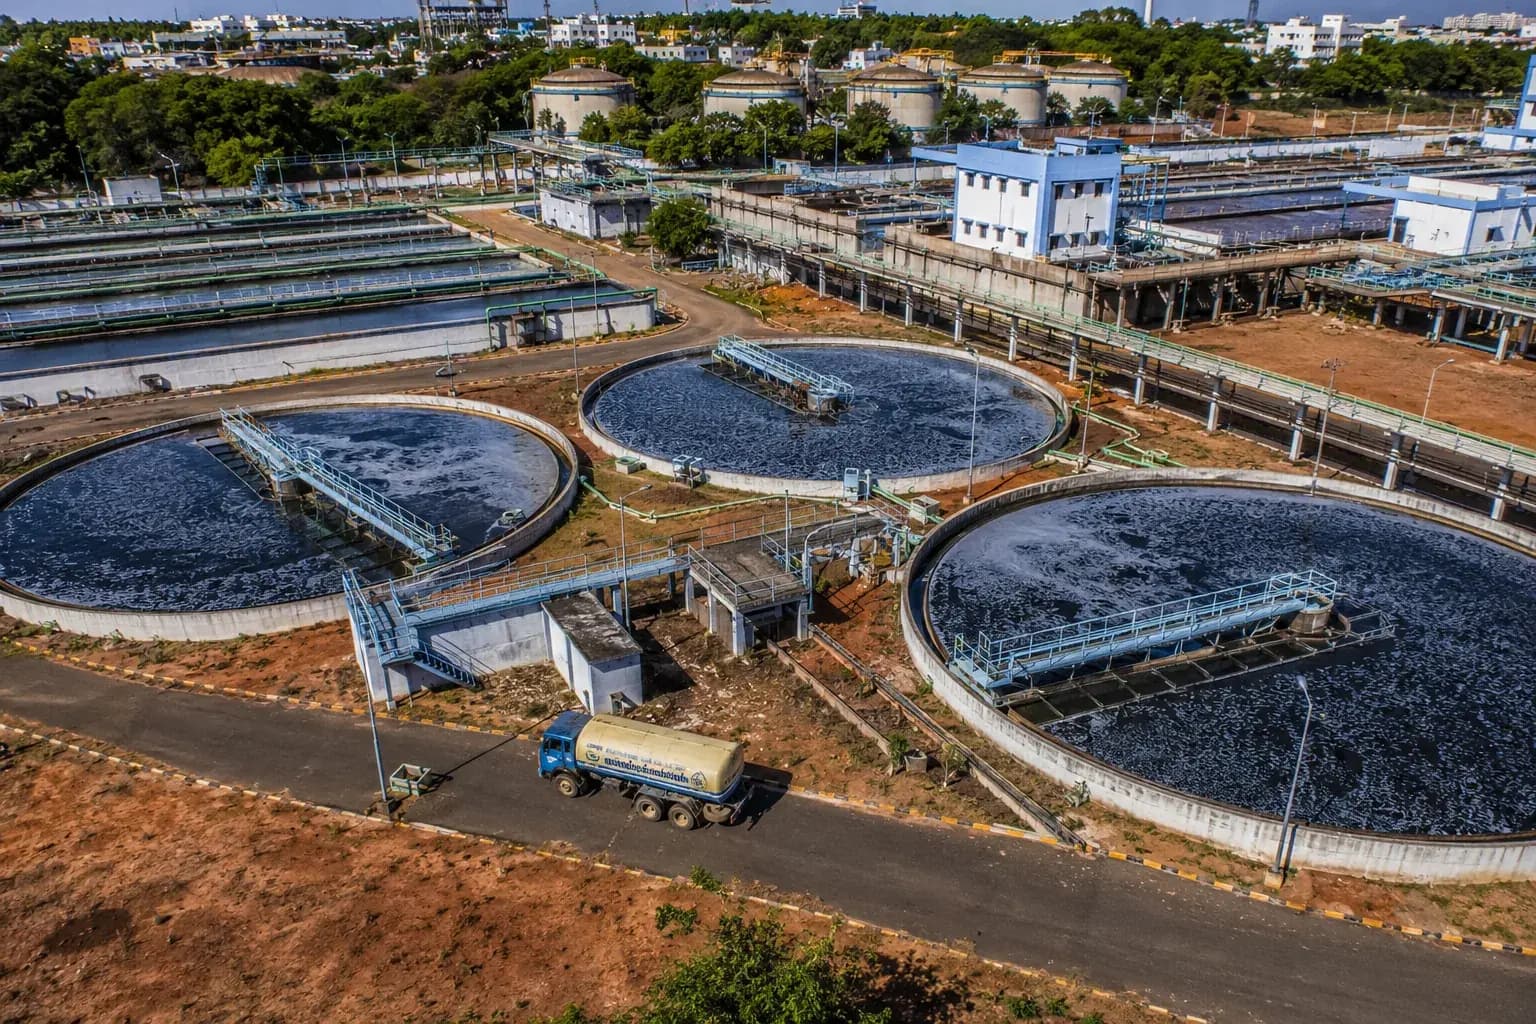
KIPL conducts third-party environmental audits of civic assets and programmes against the actual instrument that governs them (the consent conditions, the contract specification, the Rules), rather than against a general checklist. We record what we found, including what we could not verify, because an audit that reports only favourable findings is worth nothing the first time it is tested. The most common weakness we encounter is that no baseline was recorded at handover, which leaves the corporation unable to demonstrate either performance or decline.
- Rule 14, EP Rules 1986
Environmental Statement in Form-V
Every civic facility holding consent (STP, processing plant, disposal site) must file an annual Environmental Statement for the year ending 31 March by 30 September. Municipal facilities are frequently found not to have filed it.
RTI and audit exposure of programme outcomes
Completed environmental works are routinely queried through RTI and in audit paragraphs, and the corporation must be able to produce measured outcomes rather than sanction papers.
- NGT
Applications against civic bodies
Tribunal applications against corporations on sewage, waste and water body condition proceed on evidence. A documented audit trail is the difference between defending a position and conceding it.
What you receive
Written for municipal corporations, not adapted from a template.
- 01Asset-by-asset audit of civic facilities against their own consent conditions and contract specifications
- 02Verification of programme outcomes (survival counts, tonnage processed, treated volumes) with method stated
- 03Form-V Environmental Statement preparation for facilities holding consent
- 04Gap register with the responsible department, the governing provision and the corrective action
- 05Evidence pack structured to answer an RTI query or an audit paragraph without re-survey
- 06Recommendations written into a form usable in the next tender document
Questions from municipal corporations
What municipal corporations ask before appointing us.
Answered against the regulation as it stands, not as a sales pitch. If your situation is not here, ask us directly.
Ask a question →Is an environmental audit statutory for a municipal corporation?
Parts of it are. Any civic facility holding consent under the Water Act 1974 or the Air Act 1981 must file an annual Environmental Statement in Form-V under Rule 14 of the Environment (Protection) Rules 1986. Beyond that, third-party performance audit of programmes is not mandated but is increasingly how a corporation demonstrates that money spent produced a result.
What makes an audit finding hold up under RTI?
Method and traceability. Each finding needs the date, the location, the measurement method and the source document it was checked against, so that an independent reader reaches the same conclusion. Findings expressed as opinions, or without a stated method, invite exactly the follow-up query the audit was meant to close.
Should the audit be done by the same agency that executed the work?
No. A performance audit by the executing agency is not independent and will be treated as such the moment it matters. The value of a third-party audit for a public body is precisely that the auditor has nothing at stake in the finding, which is why the engagement should be separately tendered.
What if the audit finds the programme underperformed?
That is the useful outcome. A finding recorded by the corporation, with a corrective action and a date, puts the civic body in the position of having identified and acted on the problem. The damaging sequence is the opposite one, where an external applicant establishes the shortfall first and the corporation has no record of having known.
Can an audit cover a programme that had no baseline?
Partially. Where no baseline was recorded at handover, the audit can establish present condition and the compliance position against consent or contract, but it cannot certify change. We say so explicitly in the report and recommend that the present survey be fixed as the baseline for future comparison, so the gap is closed going forward.
How often should civic environmental assets be audited?
Consent-holding facilities need the annual Form-V cycle regardless. For programme assets such as plantations, gardens and restored water bodies, an audit that coincides with maintenance-period milestones and with the end of the defect liability period is the most useful, because that is when the corporation still has contractual remedy.
Stage by stage
How environmental audits actually runs, step by step.
Also for municipal corporations
The rest of the environmental brief for this sector.
Relevant proof
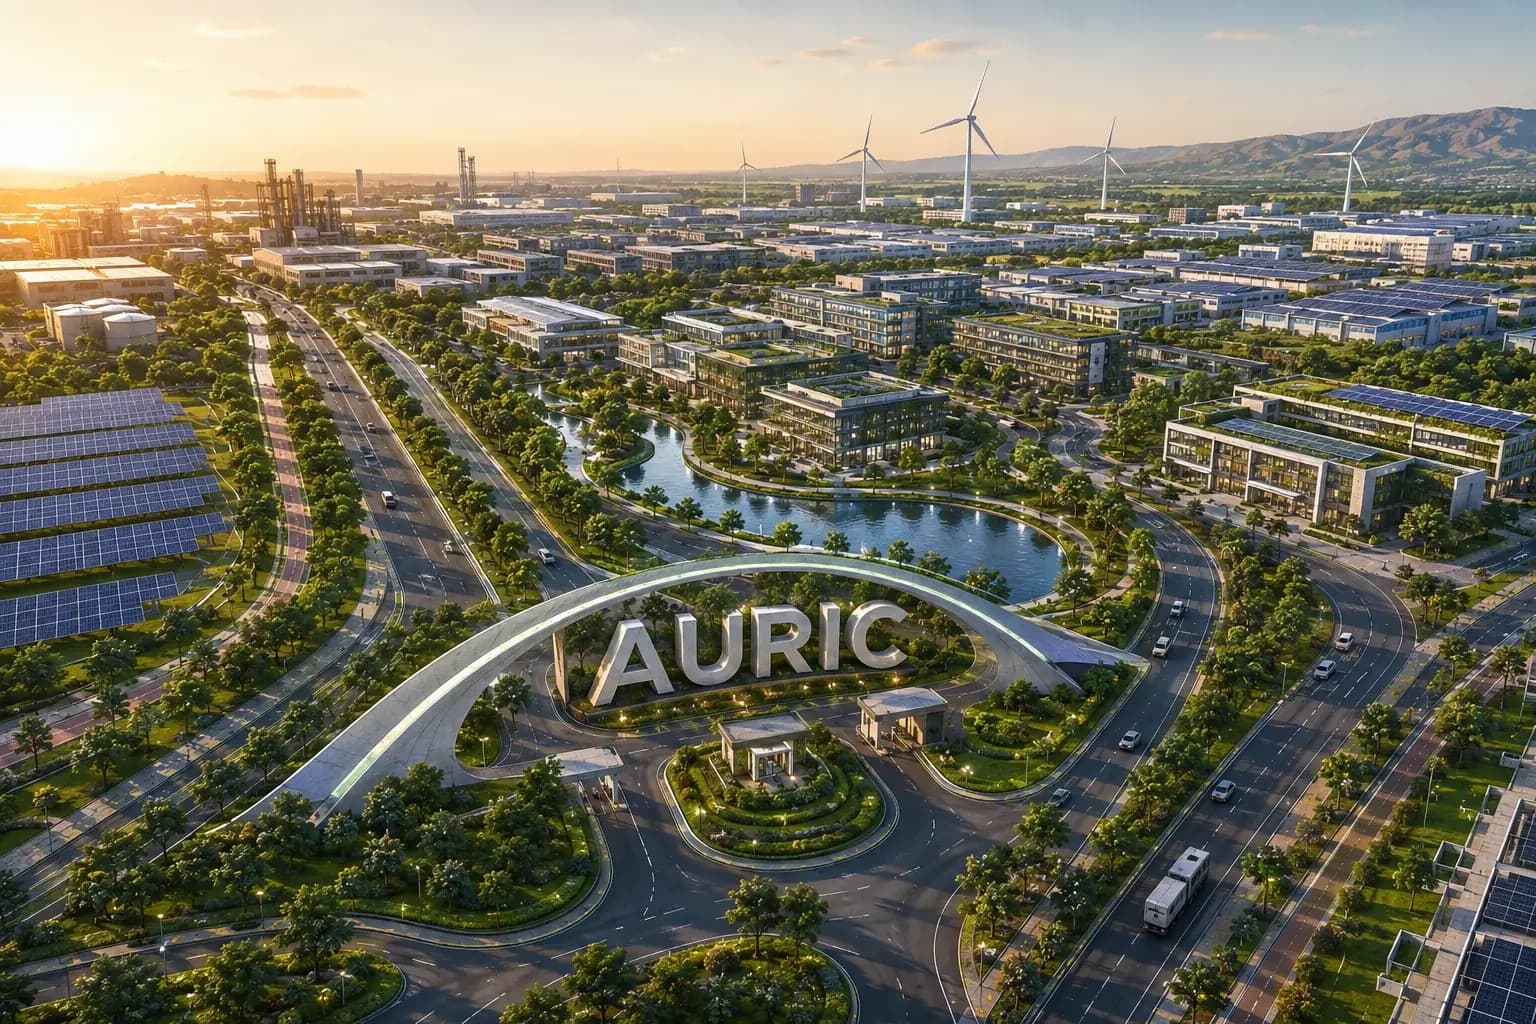
SHENDRA AND BIDKIN INDUSTRIAL AREA, AURANGABAD
Environmental compliance audits, Consent to Establish and green certification support across two industrial nodes of the Delhi-Mumbai Industrial Corridor.
- Shendra + Bidkin
- 4,024 ha
- City scale
- IGBC Gold
Where we do this
Environmental Audits for municipal corporations, city by city.
Other sectors
Who else we run environmental audits for.
Next step
Tell us the project, and we will tell you the category and the route.
Screening is the cheapest stage to get right and the most expensive to get wrong. We will say plainly what environmental audits your municipal corporations project needs, and what it does not.
Start the conversation