ESG Advisory & Reporting · Corporate Campuses
ESG Reporting Support for Corporate Campuses
BRSR disclosure by a listed parent turns campus energy, water and waste into reported figures, which means the estate team now has to measure them to a standard that will survive assurance.
Screening view on your project, with the category and route named. No obligation.
What this means for corporate campuses
The reporting obligation sits with the listed entity, but the data sits on the site. SEBI's Business Responsibility and Sustainability Reporting framework requires disclosure of energy consumption, water withdrawal and discharge, waste generated and disposed, and emissions, and the assurance requirements attaching to core indicators mean these numbers are increasingly tested rather than accepted. For a facilities or sustainability head, that changes the job: the estate is no longer asked for an annual figure at year end but for a measurement system that produces the same figure consistently and can show where it came from.
How KIPL runs it
KIPL works from the site upward: meters and their coverage, the boundary of what is included, the treatment of tenants and shared services, and the estimation methods used where measurement genuinely does not exist. The problems that surface are consistent across campuses: energy reported from utility bills that include a leased-out block, water figures that mix metered municipal supply with an unmetered borewell, waste tonnage taken from a contractor's invoice rather than a weighbridge, and a diesel generator whose hours nobody logs. Each of these is fixable, but only if it is found before the disclosure is filed rather than during assurance.
- BRSR
Listed parent disclosure pulls site data upward
SEBI's Business Responsibility and Sustainability Reporting framework requires listed entities to disclose energy, water, waste and emissions performance, which is generated at site level.
Assurance tests the evidence
Assurance over core sustainability indicators means reported figures are traced back to meters, logs and invoices, so estimates without a stated basis become findings.
Group commitments cascade to the estate
Corporate net-zero, RE100 and water stewardship commitments are delivered on the campus, and progress against them is reported from campus data.
What you receive
Written for corporate campuses, not adapted from a template.
- 01Reporting boundary definition covering owned, leased, tenanted and shared-service areas of the campus
- 02Meter and data source audit for energy, water and fuel, with coverage gaps identified
- 03Waste data reconciliation from weighment records and authorised handler manifests rather than invoices
- 04Greenhouse gas inventory for the campus with emission factors and methods documented
- 05Indicator definitions and calculation notes prepared for the assurance provider
- 06Reporting pack in the format the parent's disclosure and internal review cycle require
Questions from corporate campuses
What corporate campuses ask before appointing us.
Answered against the regulation as it stands, not as a sales pitch. If your situation is not here, ask us directly.
Ask a question →Our parent is listed, not the campus. What is our obligation?
The disclosure obligation is the listed entity's, but the data it discloses is generated at your site, and it is your records the assurance provider will examine. In practice the campus carries a data quality obligation even though it is not itself the reporting entity, and that is best formalised as a defined data request with fixed definitions rather than an annual email.
What is assured, and what is not?
SEBI's framework identifies a set of core indicators subject to assurance, phased by the size of the listed entity, while the remainder is disclosed without assurance. The practical consequence is that some campus figures will be traced to source documents and others will not, and it is worth knowing which is which before the reporting cycle starts.
Where do campus ESG numbers usually break?
Boundary and measurement. Utility bills that cover leased-out areas, unmetered borewell abstraction sitting alongside metered municipal supply, waste tonnage taken from a contractor invoice, and generator fuel with no running-hour log. All four produce numbers that cannot be reconciled when someone asks how they were derived.
How are tenanted areas handled?
By defining the boundary explicitly and disclosing it. A campus with leased-out floors must decide whether their consumption is inside or outside the reported figure and apply that consistently year on year, because a boundary that shifts between reporting cycles makes the trend meaningless and is the first thing an assurance provider will test.
Can campus plantation and green cover be reported?
Yes, as green cover, biodiversity or nature indicators supported by measurement: area, survival, species. Reporting a sequestration estimate as an offset against emissions is a different and more exposed claim, and most groups keep the two separate for that reason.
How long does it take to get a campus reporting-ready?
It depends on how much metering already exists and how many boundary questions are open. Where meters are in place, definitions can be fixed and a reporting pack built within a cycle; where sub-metering has to be installed, the timeline follows that work. The assessment that tells you which case you are in is short.
Stage by stage
How esg advisory & reporting actually runs, step by step.
Also for corporate campuses
The rest of the environmental brief for this sector.
Relevant proof
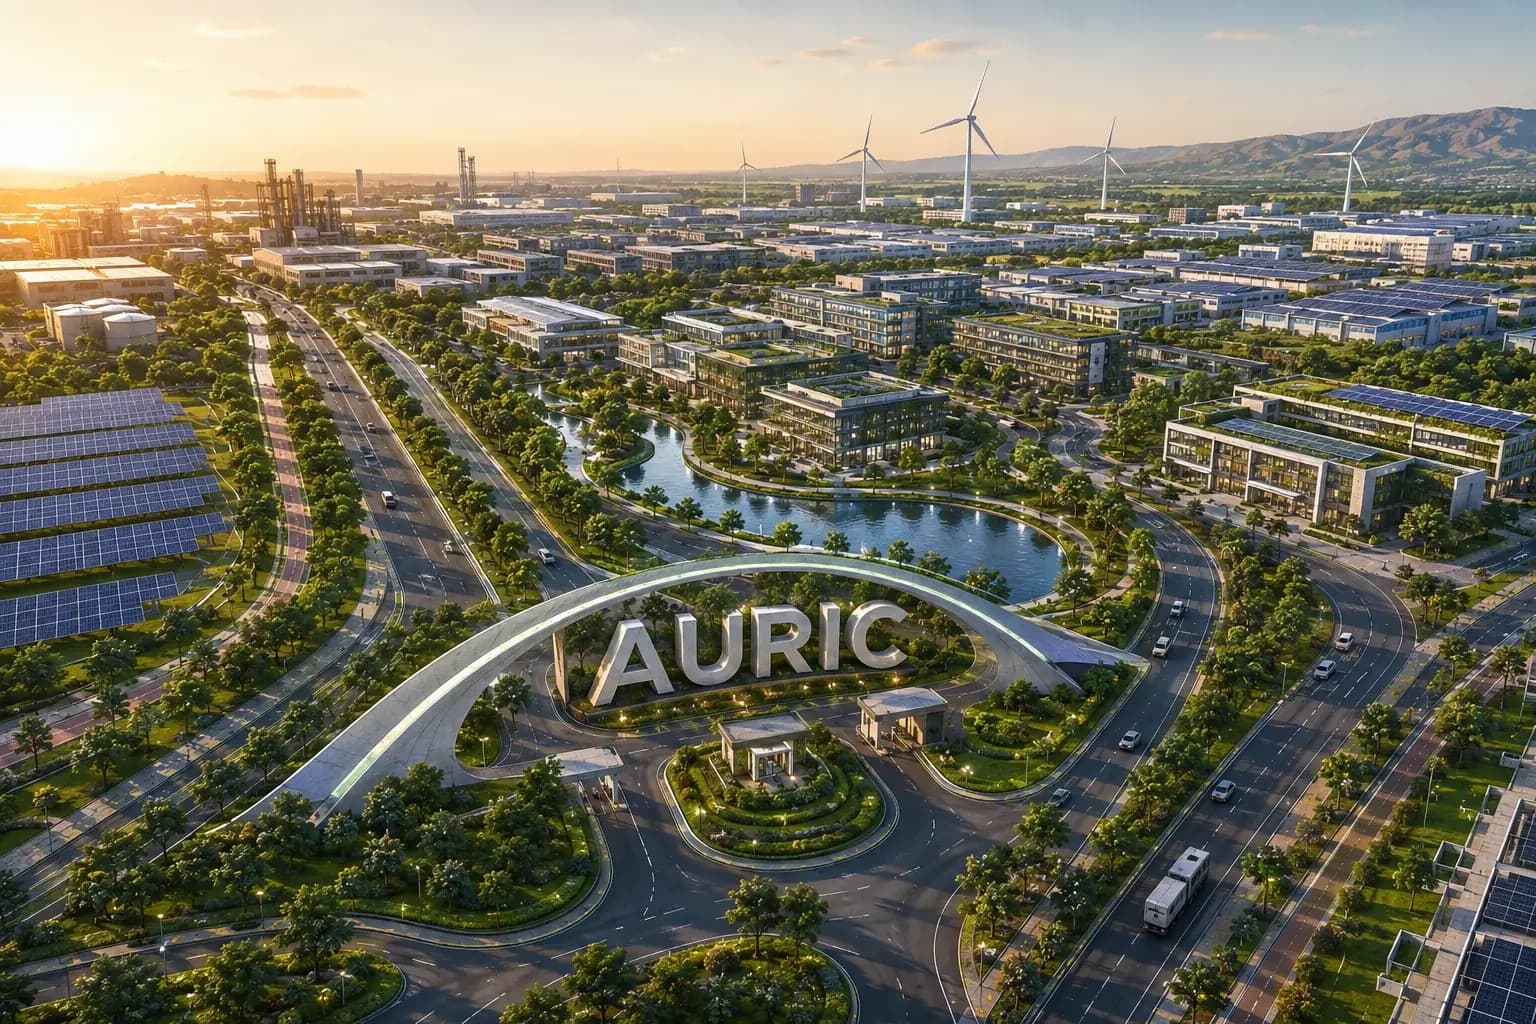
SHENDRA AND BIDKIN INDUSTRIAL AREA, AURANGABAD
Environmental compliance audits, Consent to Establish and green certification support across two industrial nodes of the Delhi-Mumbai Industrial Corridor.
- Shendra + Bidkin
- 4,024 ha
- City scale
- IGBC Gold
Where we do this
ESG Advisory & Reporting for corporate campuses, city by city.
Other sectors
Who else we run esg advisory & reporting for.
Next step
Tell us the project, and we will tell you the category and the route.
Screening is the cheapest stage to get right and the most expensive to get wrong. We will say plainly what esg advisory & reporting your corporate campuses project needs, and what it does not.
Start the conversation