ESG Strategy and Materiality: deciding which ESG issues actually matter to your business.
A materiality assessment identifies the small number of environmental, social and governance issues that genuinely affect a business and its stakeholders. And an ESG strategy is what the organisation then does about them.
What it is
Every ESG framework begins with materiality because no organisation can meaningfully manage the full universe of ESG topics. A materiality assessment tests candidate issues against two questions: how significantly does this affect our stakeholders and the environment, and how significantly does it affect our ability to create value. The answers are drawn from stakeholder engagement, peer and sector analysis, regulatory direction and the company's own risk register, and they are then prioritised with management and, where the disclosure requires it, approved by the board.
KIPL runs the assessment so that it produces decisions rather than a matrix. The material issues become the reporting boundary, the target set and the governance agenda: who owns each issue, what is measured, what is committed to, and what gets reported. For a listed entity this feeds directly into the BRSR, where the material responsible business conduct issues and their financial implications must be disclosed; for an unlisted company it is what stops ESG spending being spread thinly across topics that do not move the business.
What you get
The deliverables, in hand.
- Authority
- GRI 3 Material Topics · NGRBC principles · SEBI BRSR disclosure
- Typical timeline
- Six to twelve weeks including stakeholder engagement
- Issue universe drawn from sector, peer and framework analysis
- Stakeholder engagement: internal and external, documented
- Materiality assessment with prioritisation and board-ready rationale
- ESG strategy: objectives, targets, owners and roadmap
- Governance structure, committee terms of reference and escalation
- KPI set aligned to the reporting frameworks the organisation must meet
Straight answers
ESG Strategy & Materiality: common questions.
01What is an ESG materiality assessment?
It is a structured process for identifying which environmental, social and governance topics are significant enough to warrant management attention and disclosure, based on their impact on stakeholders and on the business. It sets the boundary for everything that follows: strategy, targets, data collection and reporting.
02What is the difference between single and double materiality?
Single materiality asks only how ESG issues affect the company financially, the investor-facing view taken by the ISSB standards. Double materiality also asks how the company affects people and the environment, which is the view GRI takes and which European reporting requires. Which one applies determines what you must assess and disclose, so it is settled at the start, not discovered later.
03Is a materiality assessment required for BRSR?
The BRSR requires a listed entity to disclose its material responsible business conduct and sustainability issues, the risks and opportunities each presents, its approach to adapting or mitigating them, and the financial implications. You cannot complete that disclosure credibly without having carried out an assessment, so it is required in substance even where the format is not prescribed.
04How often should materiality be refreshed?
A full reassessment every two to three years is the common practice, with an annual review to confirm nothing has shifted. Refresh sooner after a significant change: a major acquisition, entry into a new geography, a regulatory shift such as a new carbon or supply chain requirement, or a serious incident that changes stakeholder expectations.
05Who should be engaged in the assessment?
The stakeholders whose views actually bear on the business: investors and lenders, major customers, employees, suppliers, communities around operating sites, and regulators. Engagement should be documented, reporting frameworks and assurance providers ask how stakeholders were identified and consulted, and an assessment carried out only inside the management team is easy to challenge.
06How is it different from the company's risk register?
The risk register looks outward-in: what could harm the company. Materiality, in the double sense, also looks inward-out: what harm the company causes. They overlap substantially and should be reconciled. An issue that is material for reporting but absent from the risk register usually indicates one of the two exercises has not been done properly.
07What does an ESG strategy actually contain?
A defined set of material issues; measurable objectives and targets against each, with baselines and dates; named executive owners; the governance route by which performance is reviewed and escalated; the data and systems needed to measure it; and the disclosure commitments. Anything short of that is a statement of intent rather than a strategy.
Within ESG Advisory & Reporting
Part of the whole route, the other components.
Relevant proof
Where this stage has already been delivered.
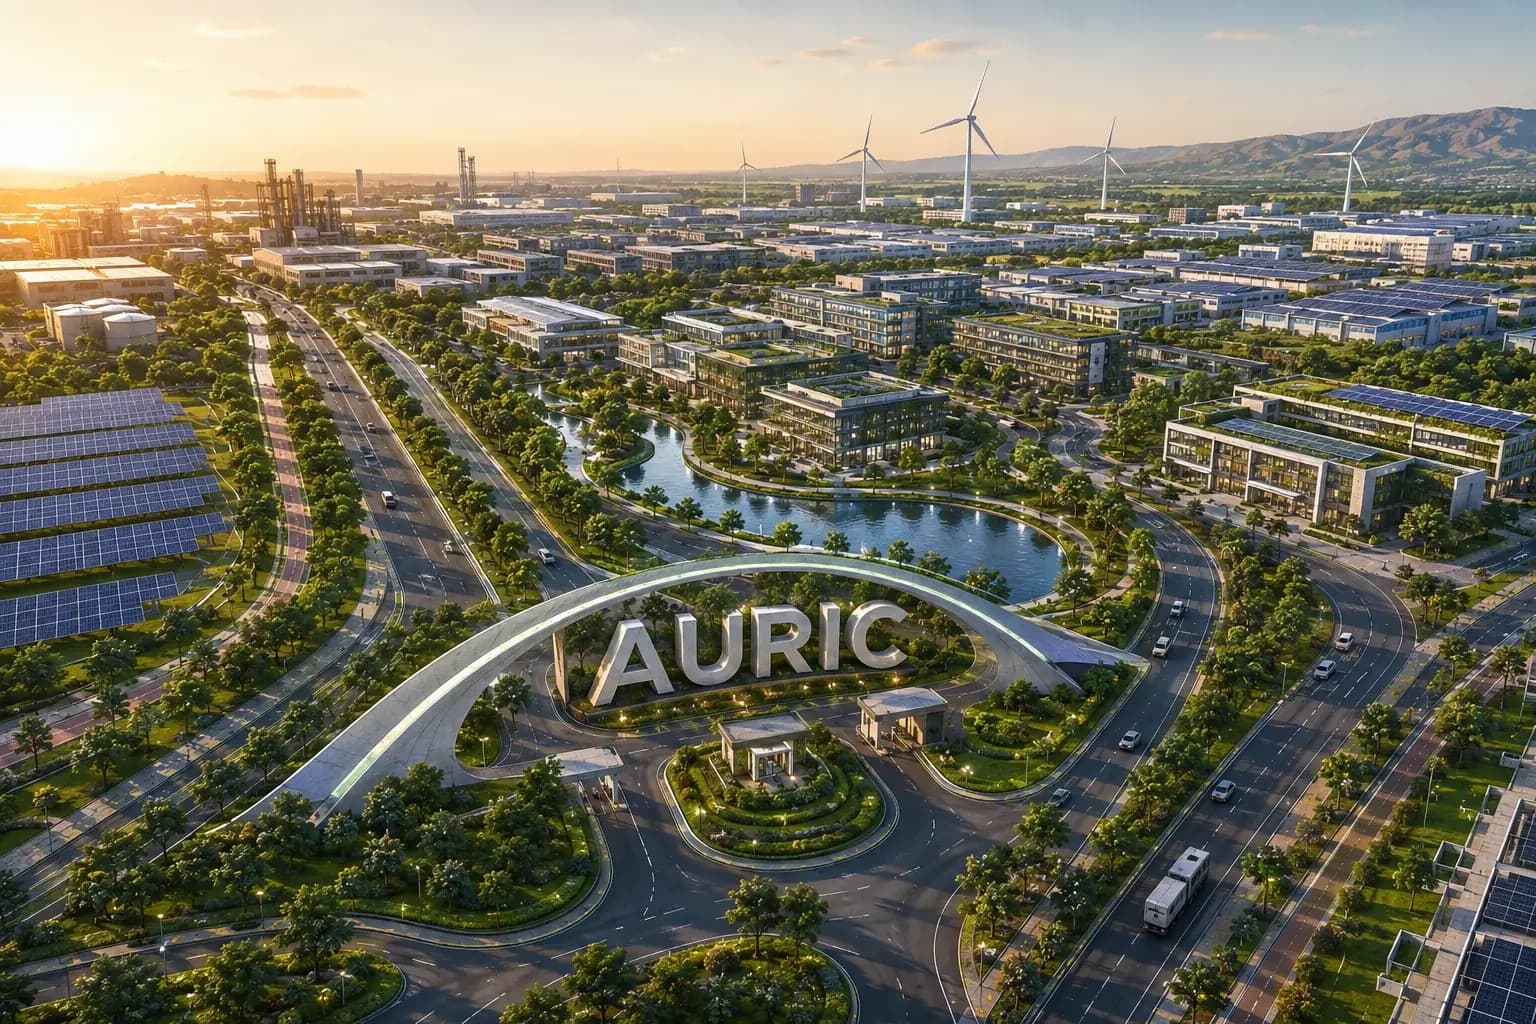
MIDC / AURIC · Shendra & Bidkin, Chhatrapati Sambhajinagar
SHENDRA AND BIDKIN INDUSTRIAL AREA, AURANGABAD
Environmental compliance audits, Consent to Establish and green certification support across two industrial nodes of the Delhi-Mumbai Industrial Corridor.
Where we do this
ESG Advisory & Reporting on the ground.
The authority, the timeline and the local ground differ by city. These pages set out how esg advisory & reporting actually runs in each.
- Ahmedabad
- Ambernath
- Andhra Pradesh
- Badlapur
- Bengaluru
- Bhiwandi
- Chennai
- Chhatrapati Sambhajinagar
- Delhi NCR
- Gandhinagar
- Goa
- Gujarat
- Gurugram
- Haryana
- Hyderabad
- Indore
- Jaipur
- Kalyan-Dombivli
- Karnataka
- Kerala
- Kharghar
- Kochi
- Kolhapur
- Kolkata
- Lucknow
- Madhya Pradesh
- Maharashtra
- Mira-Bhayandar
- Mormugao
- Mumbai
- Nagpur
- Nashik
- Navi Mumbai
- New Delhi
- Noida
- Panaji
- Panvel
- Pune
- Punjab
- Rajasthan
- Rajkot
- Solapur
- Surat
- Taloja
- Tamil Nadu
- Telangana
- Thane
- Ulhasnagar
- Uran
- Uttar Pradesh
- Vadodara
- Vasai-Virar
- Visakhapatnam
- West Bengal
Featured projects
Work that carries its own evidence.
Our expertise
One team across the whole environmental brief.
ESG Strategy & Materiality is one stage of one practice. Most projects need several, and the commitments made at clearance are the ones we build and maintain.
Who we do this for
ESG Advisory & Reporting reads differently by industry.
- 01
River & Water MissionsCore
Multilateral and national mission funding brings E&S safeguard reporting obligations that continue for the life of the programme.
ESG Advisory & Reporting for River & Water Missions - 02
Corporate CampusesCore
BRSR disclosure by the listed parent turns campus energy, water and waste numbers into figures that must be measured and assured.
ESG Advisory & Reporting for Corporate Campuses - 03
Environmental & Social Due DiligenceCore
Funds need portfolio-level E&S management systems and reporting that satisfy their own LPs and development-finance investors.
ESG Advisory & Reporting for Environmental & Social Due Diligence - 04
Data Centres & IT Parks
Operators carry public net-zero and water-positive commitments that require carbon accounting at the campus, then disclosure up the chain.
ESG Advisory & Reporting for Data Centres & IT Parks - 05
Chemical Industry
Pharma and specialty buyers now push supplier ESG data down the chain, so a mid-size chemical unit is disclosing whether or not it is listed.
ESG Advisory & Reporting for Chemical Industry - 06
Industrial & Manufacturing
BRSR obligations on listed customers push supplier ESG and Scope 3 data requests onto unlisted manufacturers in their value chain.
ESG Advisory & Reporting for Industrial & Manufacturing
Trusted by
The organisations this work is done for.
In the press