ESG Advisory & Reporting · Chemical Industry
ESG Advisory and Reporting for Chemical Manufacturers
A mid-size chemical manufacturer is now disclosing ESG data whether or not it is listed, because its pharma and specialty customers are pushing supplier requirements down the chain.
Screening view on your project, with the category and route named. No obligation.
What this means for chemical industry
The disclosure pressure on this sector does not arrive from the regulator first. It arrives from the customer. A listed company reporting under SEBI's Business Responsibility and Sustainability Report framework must extend part of its disclosure to its value chain, and its procurement function turns that into a supplier questionnaire. For a dye or intermediate maker supplying textile chains there is a second layer, in the chemical management and restricted substance programmes those chains operate. For a bulk drug intermediate supplier there is a third, in the audit protocols pharmaceutical buyers apply to their upstream vendors. The result is that an unlisted chemical unit finds itself answering for its emissions, effluent, hazardous-waste practice, water use and worker safety on someone else's template, several times a year.
How KIPL runs it
KIPL builds the disclosure from the data the plant already generates for compliance, because that is the only version that will survive an audit: consent monitoring records, hazardous-waste manifests and returns, water balance, energy and fuel consumption, incident records and the EC compliance reports. Where a metric is genuinely absent (Scope 2 emission factors, water intensity per tonne of product, waste diverted from disposal) we set up the measurement rather than estimate it. What goes wrong otherwise is a chemical company that presents a sustainability narrative its own regulatory record contradicts. A customer audit that finds an effluent exceedance in the Board's own online monitoring data, unmentioned in the ESG report, does more damage than never having reported at all.
- Value chain
Listed buyers push disclosure upstream
BRSR value-chain expectations mean a listed pharma or specialty customer collects ESG data from its unlisted chemical suppliers as a condition of doing business.
- Customer audits
Chemical management programmes
Dye and intermediate makers supplying textile and pharmaceutical chains face restricted-substance and chemical-management audit protocols that ask for effluent, emission and waste evidence directly.
- Lenders
Finance is conditioned on it
Banks and development finance institutions lending to chemical capacity apply environmental and social requirements that need reported data and a management system behind them.
What you receive
Written for chemical industry, not adapted from a template.
- 01Materiality assessment framed on what actually drives risk in a chemical unit: effluent, hazardous waste, emissions, water and process safety
- 02Data architecture drawing metrics from consent monitoring, hazardous-waste returns, water balance and energy records rather than estimates
- 03Greenhouse gas inventory for Scope 1 and Scope 2, with the fuel and power basis documented
- 04Customer and buyer questionnaire response pack, consistent across the different templates the plant is sent
- 05Disclosure report aligned to the framework the company reports under, reconciled against its regulatory record
- 06Improvement roadmap with baselines and targets tied to the plant's own operating levers
Questions from chemical industry
What chemical industry ask before appointing us.
Answered against the regulation as it stands, not as a sales pitch. If your situation is not here, ask us directly.
Ask a question →We are unlisted: why are we being asked for ESG data?
Because your customers are listed and their own disclosure obligations extend to their value chain. Procurement teams convert that into supplier questionnaires and audits, so an unlisted chemical supplier ends up reporting emissions, effluent, waste and safety data as a commercial condition rather than a regulatory one.
Where does the data come from?
Mostly from records the plant already keeps for compliance: consent monitoring, online effluent and emission data, hazardous-waste manifests and annual returns, water balance, fuel and power consumption and incident logs. Building the disclosure on those records is what makes it defensible when a customer audits it.
What is the risk of overstating performance?
In this sector, a high one. Effluent and emission data from the Board's online monitoring, hazardous-waste returns and EC compliance reports are all independently held, and an ESG report that contradicts them is discoverable by any auditor who looks. Understating a problem you have disclosed to a regulator is the worst of both positions.
Does ESG reporting help with lending?
It helps where the lender applies environmental and social requirements, which most institutional lenders to chemical capacity now do. What they assess is the management system and the evidence behind the numbers, not the report's presentation: so the useful work is establishing measurement, not writing narrative.
Should we report greenhouse gas emissions?
Scope 1 and Scope 2 are increasingly asked for by customers, and both are computable from fuel and purchased electricity records a chemical plant already keeps. Scope 3 is a larger exercise and is usually approached later, starting with purchased raw materials, which for a chemical unit is the dominant category.
How does this relate to our regulatory compliance work?
Directly. The compliance record is the raw material. It is also the reason the two should not be run by unconnected teams: a disclosure prepared in isolation from the consent, waste and clearance records almost always contains a statement the regulatory file does not support.
Stage by stage
How esg advisory & reporting actually runs, step by step.
Also for chemical industry
The rest of the environmental brief for this sector.
Relevant proof
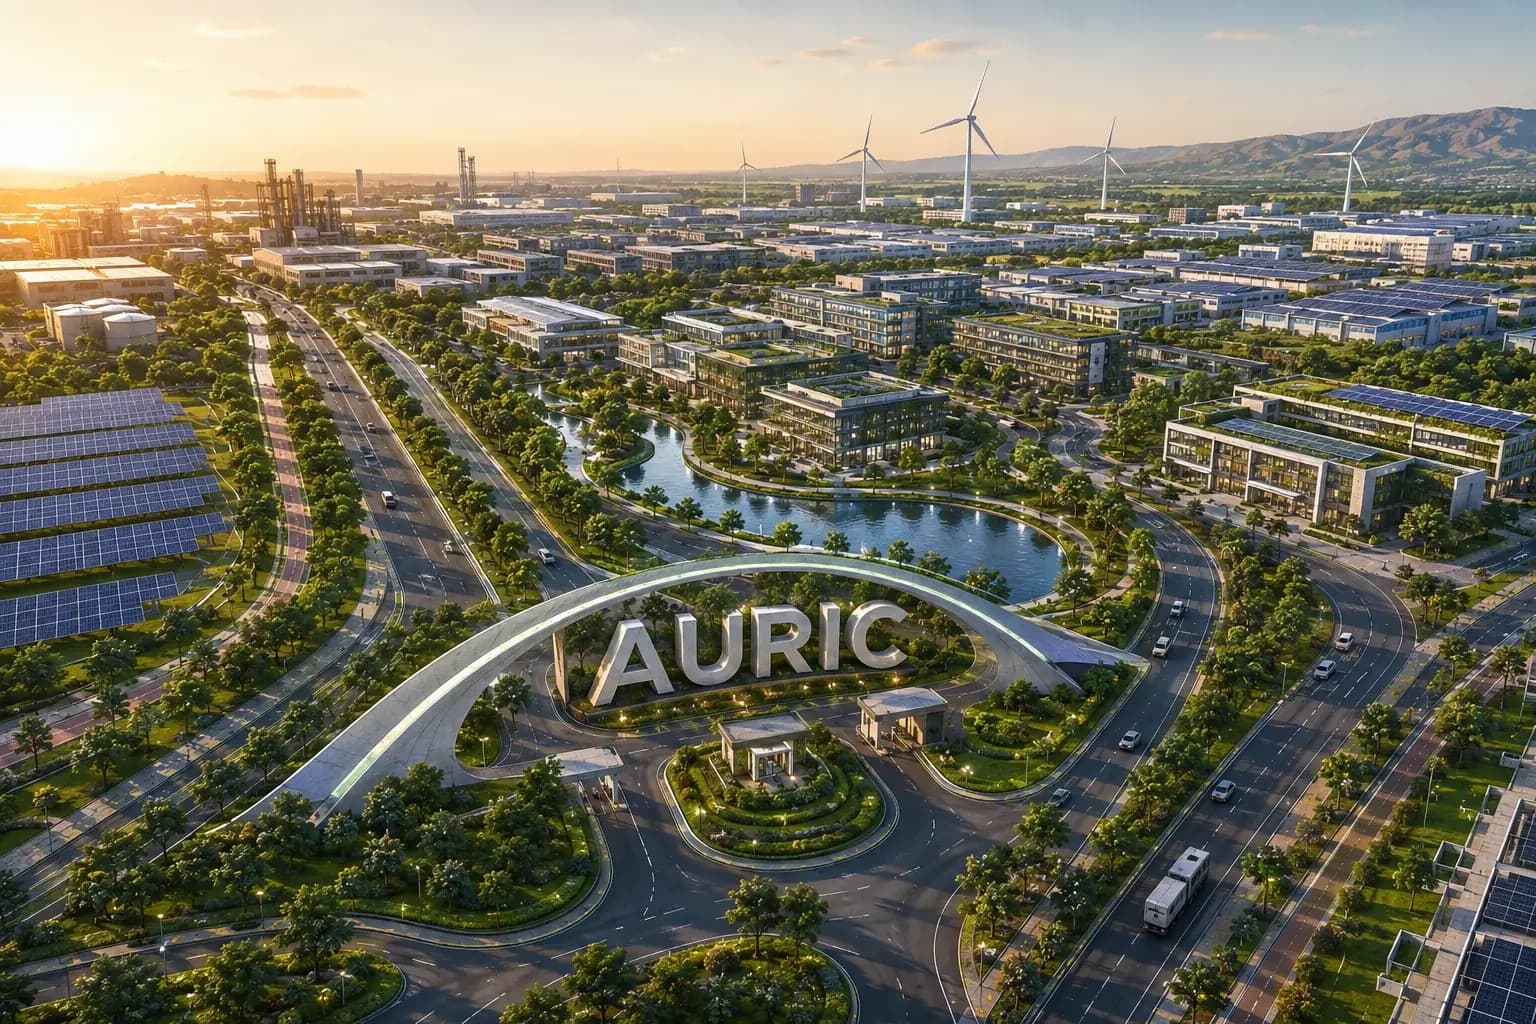
SHENDRA AND BIDKIN INDUSTRIAL AREA, AURANGABAD
Environmental compliance audits, Consent to Establish and green certification support across two industrial nodes of the Delhi-Mumbai Industrial Corridor.
- Shendra + Bidkin
- 4,024 ha
- City scale
- IGBC Gold
Where we do this
ESG Advisory & Reporting for chemical industry, city by city.
Other sectors
Who else we run esg advisory & reporting for.
Next step
Tell us the project, and we will tell you the category and the route.
Screening is the cheapest stage to get right and the most expensive to get wrong. We will say plainly what esg advisory & reporting your chemical industry project needs, and what it does not.
Start the conversation