Carbon Footprint Assessment: a measured, boundary-defined inventory of your greenhouse gas emissions.
A carbon footprint assessment is a greenhouse gas inventory: a defined boundary, activity data collected against it, and emissions calculated with documented factors so the number can be audited.
What it is
The inventory is built to a recognised standard: most commonly the GHG Protocol Corporate Standard, or ISO 14064-1 where certification is intended. Boundaries are set first: which entities are consolidated and on what basis, and which emission sources fall into Scope 1 (direct combustion and process emissions), Scope 2 (purchased electricity, steam and heat) and Scope 3 (the fifteen categories of value chain emissions). Activity data is then collected (fuel, electricity, refrigerants, process inputs, logistics, procurement) and converted using factors that must be cited and justified, not assumed.
KIPL builds inventories that hold up under verification, which means traceability more than sophistication. Grid electricity in India is converted using the Central Electricity Authority baseline database rather than a generic international factor; process emissions are calculated from measured inputs; refrigerant losses are estimated from service records rather than ignored; and a base year is fixed with a recalculation policy so future targets remain comparable when the business changes shape.
What you get
The deliverables, in hand.
- Authority
- GHG Protocol Corporate Standard · ISO 14064-1 · CEA emission factors
- Typical timeline
- Six to twelve weeks for a first inventory
- Organisational and operational boundary definition with consolidation basis
- Scope 1 and Scope 2 inventory, location-based and market-based
- Scope 3 screening and calculation of material categories
- Emission factor register with sources and justification
- Base year, recalculation policy and inventory management plan
- Verification-ready data pack and calculation workbook
Straight answers
Carbon Footprint Assessment: common questions.
01What is the difference between Scope 1, 2 and 3?
Scope 1 is direct emissions from sources the company owns or controls: fuel combustion, process emissions, refrigerant leakage, owned vehicles. Scope 2 is indirect emissions from purchased electricity, steam, heating and cooling. Scope 3 is everything else in the value chain across fifteen defined categories: purchased goods and services, transport, business travel, use of sold products, and so on. For most manufacturers Scope 3 is the largest and the hardest.
02Which standard should the inventory be built to?
The GHG Protocol Corporate Standard is the default and underpins almost every other framework, including BRSR, CDP and SBTi submissions. ISO 14064-1 is used where the organisation wants a certifiable inventory with a formal validation and verification route. They are compatible; the choice is driven by whether you need a certificate or a credible number.
03What is the difference between location-based and market-based Scope 2?
Location-based uses the average emission intensity of the grid the site draws from. Market-based reflects the electricity a company has contractually purchased: renewable power purchase agreements, open access, green tariffs or certificates. Both should be reported. A company that has procured renewable energy sees the benefit only in the market-based figure, which is why the distinction is worth understanding before making a claim.
04Which emission factors apply in India?
For grid electricity, the CO2 baseline database for the Indian power sector published by the Central Electricity Authority is the appropriate source. For fuels and process emissions, IPCC default factors are widely used, with national or measured values where available. What matters as much as the choice is that each factor is documented with its source and vintage, because that is the first thing a verifier will test.
05Is measuring a carbon footprint mandatory in India?
For some entities, in effect. The BRSR requires listed entities within its scope to disclose Scope 1 and Scope 2 emissions and encourages Scope 3. Separately, obligated entities under the Carbon Credit Trading Scheme established under the amended Energy Conservation Act face compliance obligations tied to greenhouse gas intensity. Beyond those, it is driven by customers, lenders and investors rather than by statute.
06What is a base year and why does it matter?
The base year is the reference against which reductions are measured. It must be a year with reliable data, and it needs a recalculation policy so that acquisitions, divestments and methodology changes do not make an apparent reduction that reflects a change in the boundary rather than a change in emissions. Targets set without a fixed base year and recalculation rule are not verifiable.
07Does the inventory need third-party verification?
Not always, but it depends on the use. Verification is required for SBTi validation in practice, expected for high CDP scores, and required for assurance where the figure enters an assured disclosure such as BRSR Core. Even where not required, a verified inventory is far harder to challenge, and the discipline of preparing for verification usually improves the number itself.
Within ESG Advisory & Reporting
Part of the whole route, the other components.
Relevant proof
Where this stage has already been delivered.
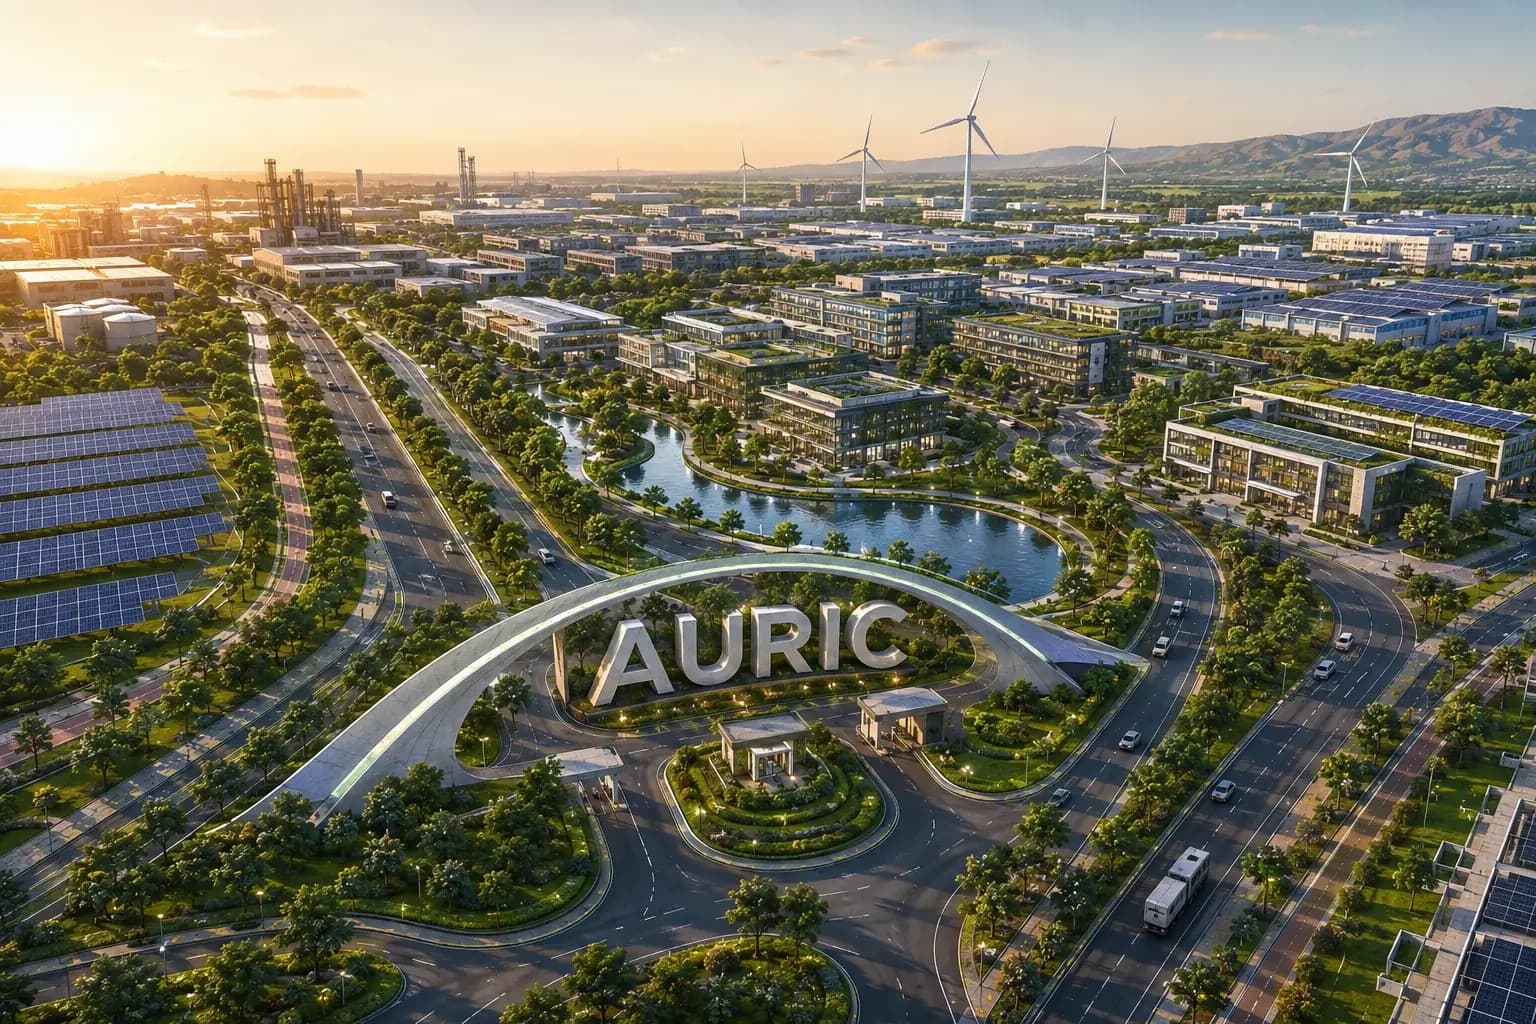
MIDC / AURIC · Shendra & Bidkin, Chhatrapati Sambhajinagar
SHENDRA AND BIDKIN INDUSTRIAL AREA, AURANGABAD
Environmental compliance audits, Consent to Establish and green certification support across two industrial nodes of the Delhi-Mumbai Industrial Corridor.
Where we do this
ESG Advisory & Reporting on the ground.
The authority, the timeline and the local ground differ by city. These pages set out how esg advisory & reporting actually runs in each.
- Ahmedabad
- Ambernath
- Andhra Pradesh
- Badlapur
- Bengaluru
- Bhiwandi
- Chennai
- Chhatrapati Sambhajinagar
- Delhi NCR
- Gandhinagar
- Goa
- Gujarat
- Gurugram
- Haryana
- Hyderabad
- Indore
- Jaipur
- Kalyan-Dombivli
- Karnataka
- Kerala
- Kharghar
- Kochi
- Kolhapur
- Kolkata
- Lucknow
- Madhya Pradesh
- Maharashtra
- Mira-Bhayandar
- Mormugao
- Mumbai
- Nagpur
- Nashik
- Navi Mumbai
- New Delhi
- Noida
- Panaji
- Panvel
- Pune
- Punjab
- Rajasthan
- Rajkot
- Solapur
- Surat
- Taloja
- Tamil Nadu
- Telangana
- Thane
- Ulhasnagar
- Uran
- Uttar Pradesh
- Vadodara
- Vasai-Virar
- Visakhapatnam
- West Bengal
Featured projects
Work that carries its own evidence.
Our expertise
One team across the whole environmental brief.
Carbon Footprint Assessment is one stage of one practice. Most projects need several, and the commitments made at clearance are the ones we build and maintain.
Who we do this for
ESG Advisory & Reporting reads differently by industry.
- 01
River & Water MissionsCore
Multilateral and national mission funding brings E&S safeguard reporting obligations that continue for the life of the programme.
ESG Advisory & Reporting for River & Water Missions - 02
Corporate CampusesCore
BRSR disclosure by the listed parent turns campus energy, water and waste numbers into figures that must be measured and assured.
ESG Advisory & Reporting for Corporate Campuses - 03
Environmental & Social Due DiligenceCore
Funds need portfolio-level E&S management systems and reporting that satisfy their own LPs and development-finance investors.
ESG Advisory & Reporting for Environmental & Social Due Diligence - 04
Data Centres & IT Parks
Operators carry public net-zero and water-positive commitments that require carbon accounting at the campus, then disclosure up the chain.
ESG Advisory & Reporting for Data Centres & IT Parks - 05
Chemical Industry
Pharma and specialty buyers now push supplier ESG data down the chain, so a mid-size chemical unit is disclosing whether or not it is listed.
ESG Advisory & Reporting for Chemical Industry - 06
Industrial & Manufacturing
BRSR obligations on listed customers push supplier ESG and Scope 3 data requests onto unlisted manufacturers in their value chain.
ESG Advisory & Reporting for Industrial & Manufacturing
Trusted by
The organisations this work is done for.
In the press