BRSR Reporting: SEBI's mandatory sustainability disclosure for India's largest listed companies.
The Business Responsibility and Sustainability Report is SEBI's prescribed sustainability disclosure, filed with the annual report by the top listed entities and structured around the nine NGRBC principles.
What it is
The BRSR replaced the older Business Responsibility Report and is filed under the SEBI Listing Obligations and Disclosure Requirements Regulations. It runs in three sections: general disclosures about the entity, management and process disclosures covering policies against each of the nine principles of the National Guidelines on Responsible Business Conduct, and principle-wise performance with quantitative data on energy, emissions, water, waste, employees, safety, community and governance. A defined subset of these data points, the BRSR Core, carries a set of specified attributes and is subject to assurance, phased by market-capitalisation rank.
KIPL treats BRSR primarily as a data problem rather than a drafting problem, because that is where organisations actually fail. Energy figures must reconcile to utility bills, emissions to activity data and defensible factors, water to metering, waste to manifests, and employee and safety numbers to HR and incident systems: and under assurance, every one of those must have a traceable source. We build the collection architecture, prepare the disclosure, and get the evidence into a state where an assurance provider can follow it back to source.
What you get
The deliverables, in hand.
- Authority
- SEBI LODR Regulations · NGRBC 2019 · SEBI BRSR circulars
- Typical timeline
- Aligned to the annual report cycle; start well before year end
- BRSR gap assessment against the current SEBI format
- Data collection architecture with defined sources, owners and controls
- Section A, B and C disclosures drafted with supporting evidence files
- BRSR Core readiness, attribute-wise evidence and control review
- Assurance support, including responses to the assurance provider
- Board and committee briefing on disclosures and their implications
Straight answers
BRSR Reporting: common questions.
01What is the BRSR?
The Business Responsibility and Sustainability Report is a standardised sustainability disclosure that SEBI requires specified listed entities to include in their annual report. It is structured around the nine principles of the National Guidelines on Responsible Business Conduct and combines narrative policy disclosures with quantitative performance data on environmental, social and governance parameters.
02Which companies must file a BRSR?
SEBI made the BRSR mandatory for the top listed entities by market capitalisation, effective from financial year 2022-23, replacing the earlier Business Responsibility Report. The applicability threshold and the phasing of associated requirements have been revised by successive SEBI circulars, so an entity near the boundary should confirm its current position against the latest circular rather than assume.
03What is BRSR Core, and how does it differ from the BRSR?
BRSR Core is a defined subset of key performance indicators drawn from the BRSR, with specified attributes intended to make them comparable and verifiable. Its distinguishing feature is assurance: the BRSR as a whole is a disclosure, while BRSR Core carries an assurance requirement phased by market-capitalisation rank. In practical terms, Core is the part where your data has to survive an external examination.
04Who can provide BRSR Core assurance?
SEBI requires the assurance provider to have the necessary expertise and, critically, to be free of conflict, it must not be providing audit or non-audit services to the entity or its group that would compromise independence. This rules out simply extending the statutory auditor's engagement, and it is a point boards should settle early rather than at year end.
05How is BRSR different from GRI reporting?
BRSR is mandatory, prescribed in format, filed with a regulator and structured on the NGRBC principles. GRI is voluntary, internationally recognised, impact-focused and organised by material topics. They draw on much of the same underlying data, and BRSR permits cross-referencing to other frameworks where the disclosure has already been made: so a company reporting under both should build one data set, not two.
06What are the nine principles the BRSR is built on?
They come from the National Guidelines on Responsible Business Conduct, 2019, and cover ethics and transparency, sustainable and safe goods and services, employee wellbeing, stakeholder responsiveness, human rights, environmental protection, responsible public policy engagement, inclusive growth and equitable development, and responsible consumer engagement. Section C of the BRSR reports performance principle by principle.
07When should preparation start?
Well before the financial year closes, not after. The disclosures require data that many organisations do not routinely collect (Scope 1 and 2 emissions, water withdrawal by source, waste by category and disposal route, complaint and grievance statistics) and retrofitting a year of that at reporting time produces figures that will not withstand assurance. The first year is a systems build; subsequent years are a reporting exercise.
Within ESG Advisory & Reporting
Part of the whole route, the other components.
Relevant proof
Where this stage has already been delivered.
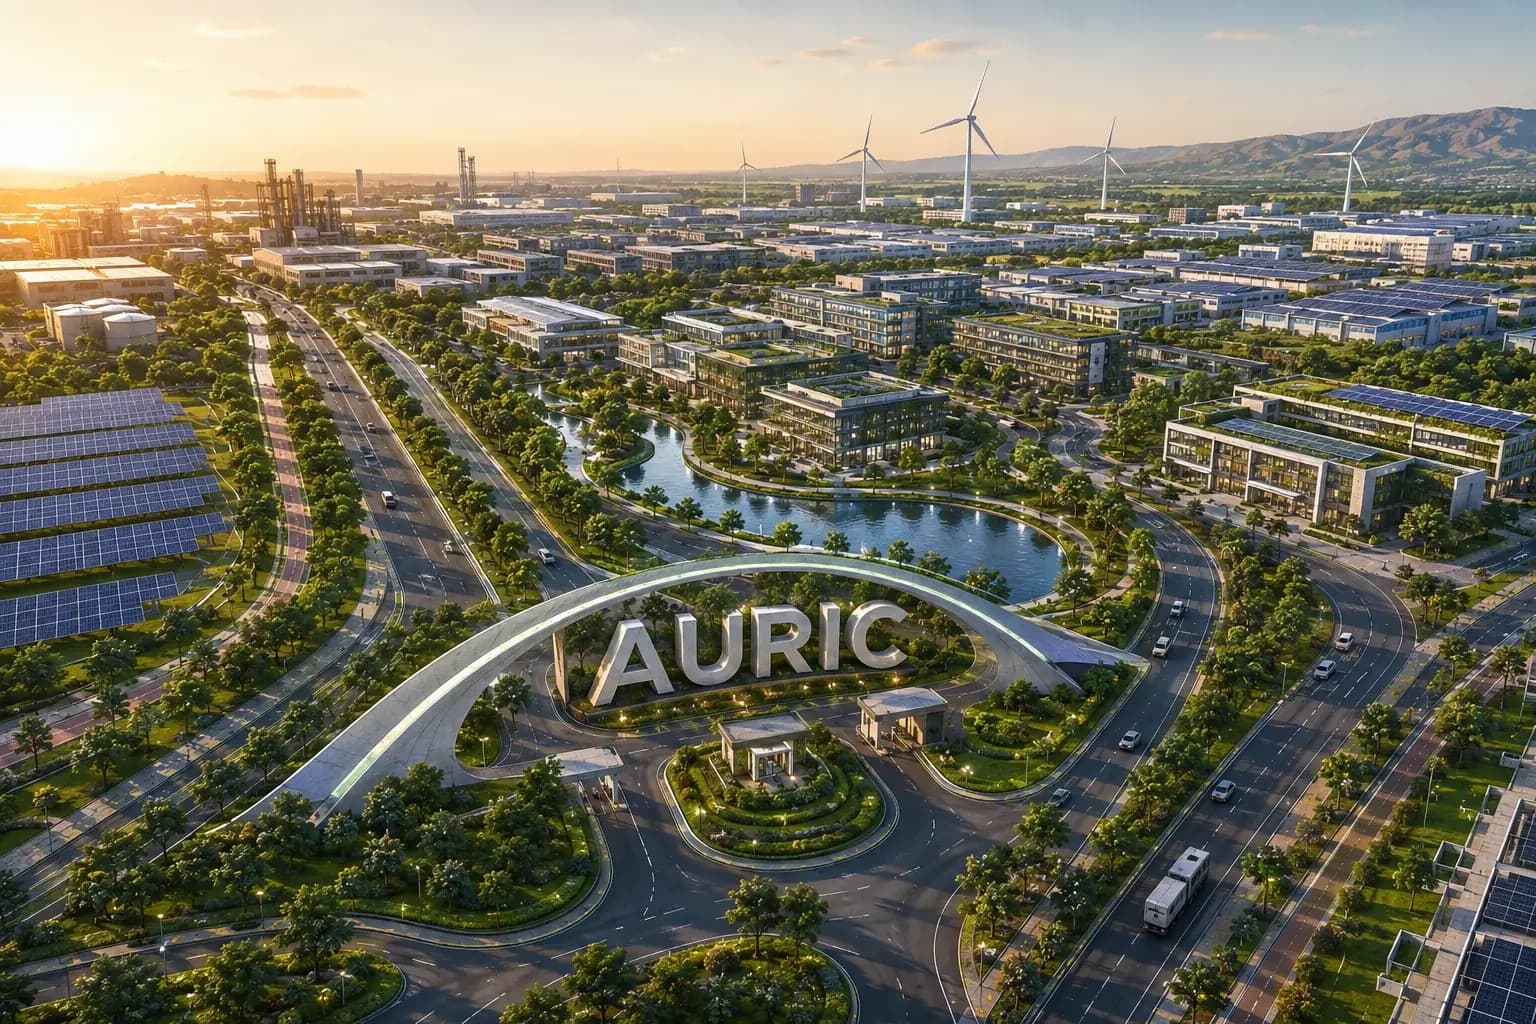
MIDC / AURIC · Shendra & Bidkin, Chhatrapati Sambhajinagar
SHENDRA AND BIDKIN INDUSTRIAL AREA, AURANGABAD
Environmental compliance audits, Consent to Establish and green certification support across two industrial nodes of the Delhi-Mumbai Industrial Corridor.
Where we do this
ESG Advisory & Reporting on the ground.
The authority, the timeline and the local ground differ by city. These pages set out how esg advisory & reporting actually runs in each.
- Ahmedabad
- Ambernath
- Andhra Pradesh
- Badlapur
- Bengaluru
- Bhiwandi
- Chennai
- Chhatrapati Sambhajinagar
- Delhi NCR
- Gandhinagar
- Goa
- Gujarat
- Gurugram
- Haryana
- Hyderabad
- Indore
- Jaipur
- Kalyan-Dombivli
- Karnataka
- Kerala
- Kharghar
- Kochi
- Kolhapur
- Kolkata
- Lucknow
- Madhya Pradesh
- Maharashtra
- Mira-Bhayandar
- Mormugao
- Mumbai
- Nagpur
- Nashik
- Navi Mumbai
- New Delhi
- Noida
- Panaji
- Panvel
- Pune
- Punjab
- Rajasthan
- Rajkot
- Solapur
- Surat
- Taloja
- Tamil Nadu
- Telangana
- Thane
- Ulhasnagar
- Uran
- Uttar Pradesh
- Vadodara
- Vasai-Virar
- Visakhapatnam
- West Bengal
Featured projects
Work that carries its own evidence.
Our expertise
One team across the whole environmental brief.
BRSR Reporting is one stage of one practice. Most projects need several, and the commitments made at clearance are the ones we build and maintain.
Who we do this for
ESG Advisory & Reporting reads differently by industry.
- 01
River & Water MissionsCore
Multilateral and national mission funding brings E&S safeguard reporting obligations that continue for the life of the programme.
ESG Advisory & Reporting for River & Water Missions - 02
Corporate CampusesCore
BRSR disclosure by the listed parent turns campus energy, water and waste numbers into figures that must be measured and assured.
ESG Advisory & Reporting for Corporate Campuses - 03
Environmental & Social Due DiligenceCore
Funds need portfolio-level E&S management systems and reporting that satisfy their own LPs and development-finance investors.
ESG Advisory & Reporting for Environmental & Social Due Diligence - 04
Data Centres & IT Parks
Operators carry public net-zero and water-positive commitments that require carbon accounting at the campus, then disclosure up the chain.
ESG Advisory & Reporting for Data Centres & IT Parks - 05
Chemical Industry
Pharma and specialty buyers now push supplier ESG data down the chain, so a mid-size chemical unit is disclosing whether or not it is listed.
ESG Advisory & Reporting for Chemical Industry - 06
Industrial & Manufacturing
BRSR obligations on listed customers push supplier ESG and Scope 3 data requests onto unlisted manufacturers in their value chain.
ESG Advisory & Reporting for Industrial & Manufacturing
Trusted by
The organisations this work is done for.
In the press