GRI and CDP Reporting: voluntary disclosure to the frameworks your investors and customers read.
GRI and CDP are the two voluntary disclosures most often asked of Indian companies, GRI as a full sustainability report, CDP as a scored questionnaire on climate, water and forests.
What it is
The GRI Standards are the most widely used international framework for sustainability reporting: universal standards covering the reporting basis, governance and material topics, plus topic and sector standards for the issues an organisation identifies as material. CDP works differently: it is an annual questionnaire, submitted on its own cycle, in which companies disclose climate change, water security and forests data, and receive a graded score that investors and large corporate customers use as a screen. Many Indian companies now respond because a customer or a lender asked, not because they chose to.
KIPL prepares both from a single, reconciled data foundation, so the GRI report, the CDP response and the statutory BRSR do not tell three different versions of the same year. For CDP specifically the work is score-driven: the questionnaire rewards governance evidence, target quality, verification and scenario analysis in ways that are not obvious from the questions, and the difference between a disclosure-level and a management-level score is usually process evidence rather than performance.
What you get
The deliverables, in hand.
- Authority
- GRI Universal Standards 2021 · CDP annual disclosure cycle
- Typical timeline
- Eight to sixteen weeks; CDP is fixed to its own cycle
- Framework selection and disclosure roadmap across GRI, CDP and BRSR
- GRI content index with material topic and boundary determination
- Full GRI-referenced or in-accordance sustainability report
- CDP questionnaire response with supporting evidence pack
- Score gap analysis against the current CDP scoring methodology
- Verification readiness for emissions and other assured data
Straight answers
GRI / CDP Reporting: common questions.
01What are the GRI Standards?
They are the international sustainability reporting framework maintained by the Global Reporting Initiative, comprising universal standards on the reporting basis, general disclosures and material topics, together with sector and topic standards. GRI takes an impact view: it reports how an organisation affects the economy, environment and people, not only how sustainability affects the organisation.
02What is CDP?
CDP runs an annual environmental disclosure system on behalf of investors and purchasing organisations, covering climate change, water security and forests. Companies complete a questionnaire and receive a score from A down to D-, with a lower grade for non-response. It is a scored benchmark rather than a report, which changes how you prepare for it.
03How do GRI and CDP differ in practice?
GRI produces a narrative report you publish and control. CDP is a structured questionnaire you submit into a scoring methodology you do not control, on a fixed annual cycle. GRI is broad across ESG topics; CDP is deep on environmental themes. Most companies that do both build one data set and present it two ways.
04Are GRI and CDP mandatory in India?
No. Neither is required by Indian law. They become effectively compulsory through commercial pressure: an investor with a stewardship policy, a multinational customer that scores its suppliers through CDP, or a lender that expects a recognised reporting framework. Companies typically start because a counterparty asked.
05How does CDP scoring work?
Responses are assessed against levels (disclosure, awareness, management and leadership) with a band assigned from A to D-. Points come not only from performance but from evidence of governance, board oversight, target setting, third-party verification and scenario analysis. A company with good emissions performance and weak process documentation routinely scores below one with the reverse profile.
06How do these relate to the BRSR?
They overlap substantially in underlying data, and the BRSR permits cross-referencing where a disclosure has already been made under another recognised framework. The practical discipline is to build one governed data set for the year and derive all three outputs from it, because three separately assembled numbers for the same parameter is a finding waiting to happen.
07What has happened to TCFD?
The Task Force on Climate-related Financial Disclosures completed its work and its recommendations have been absorbed into the IFRS Sustainability Disclosure Standards issued by the ISSB, with the ISSB taking over monitoring of climate-related disclosure. The four-pillar structure (governance, strategy, risk management, metrics and targets) remains the organising logic, so TCFD-aligned work already done is not wasted.
Within ESG Advisory & Reporting
Part of the whole route, the other components.
Relevant proof
Where this stage has already been delivered.
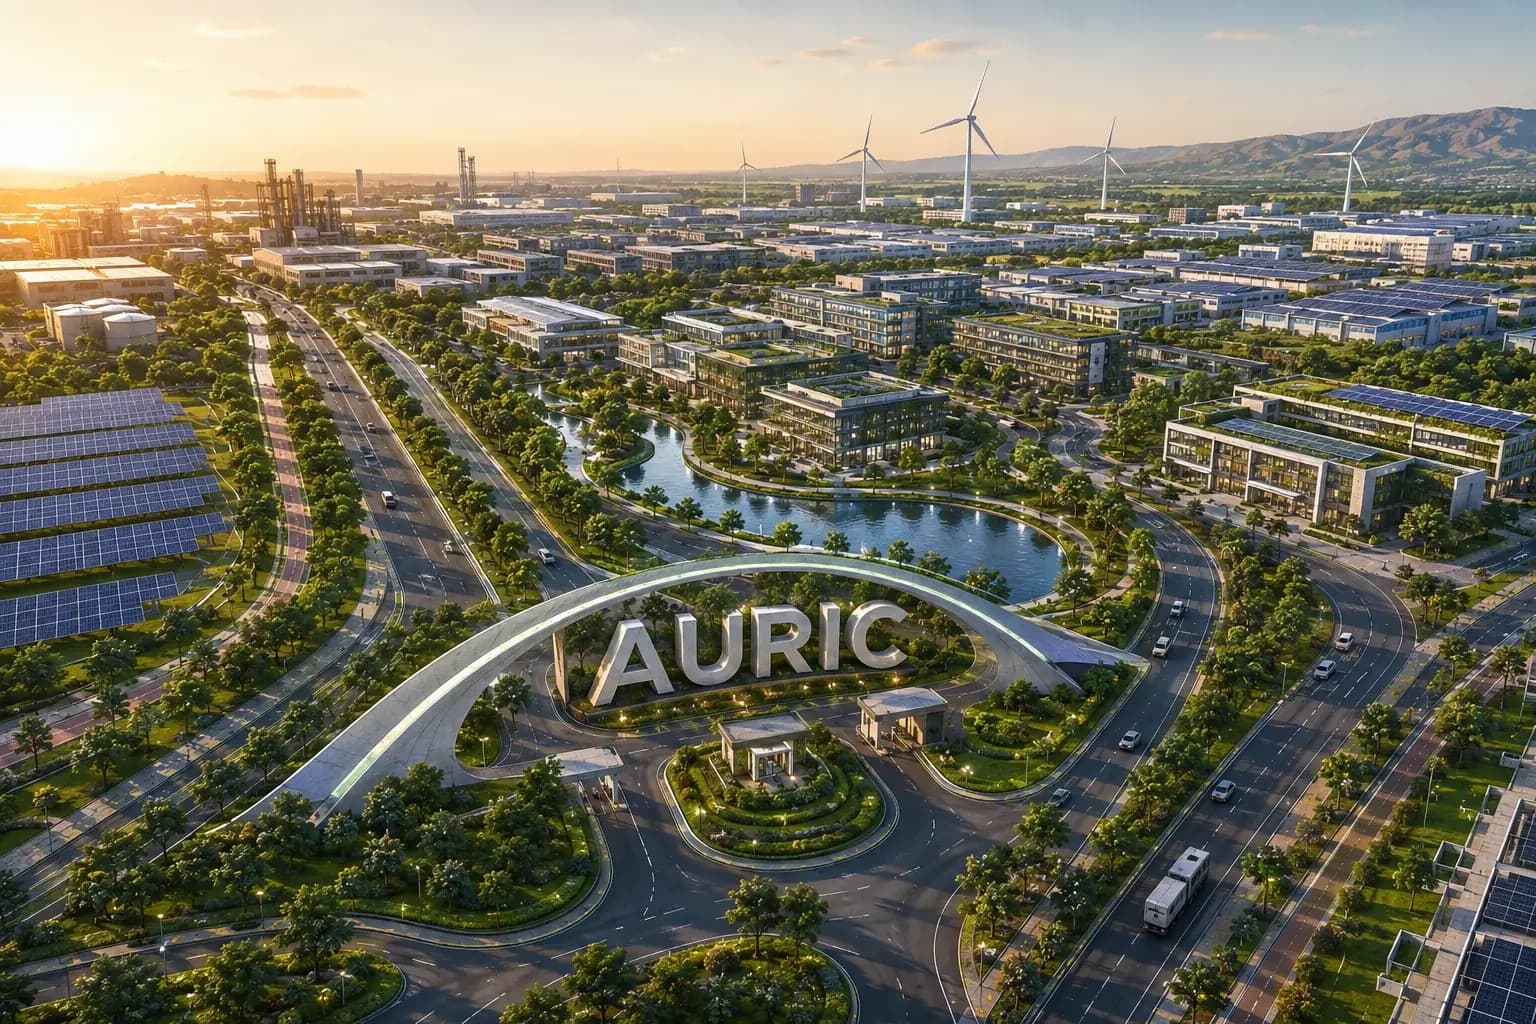
MIDC / AURIC · Shendra & Bidkin, Chhatrapati Sambhajinagar
SHENDRA AND BIDKIN INDUSTRIAL AREA, AURANGABAD
Environmental compliance audits, Consent to Establish and green certification support across two industrial nodes of the Delhi-Mumbai Industrial Corridor.
Where we do this
ESG Advisory & Reporting on the ground.
The authority, the timeline and the local ground differ by city. These pages set out how esg advisory & reporting actually runs in each.
- Ahmedabad
- Ambernath
- Andhra Pradesh
- Badlapur
- Bengaluru
- Bhiwandi
- Chennai
- Chhatrapati Sambhajinagar
- Delhi NCR
- Gandhinagar
- Goa
- Gujarat
- Gurugram
- Haryana
- Hyderabad
- Indore
- Jaipur
- Kalyan-Dombivli
- Karnataka
- Kerala
- Kharghar
- Kochi
- Kolhapur
- Kolkata
- Lucknow
- Madhya Pradesh
- Maharashtra
- Mira-Bhayandar
- Mormugao
- Mumbai
- Nagpur
- Nashik
- Navi Mumbai
- New Delhi
- Noida
- Panaji
- Panvel
- Pune
- Punjab
- Rajasthan
- Rajkot
- Solapur
- Surat
- Taloja
- Tamil Nadu
- Telangana
- Thane
- Ulhasnagar
- Uran
- Uttar Pradesh
- Vadodara
- Vasai-Virar
- Visakhapatnam
- West Bengal
Featured projects
Work that carries its own evidence.
Our expertise
One team across the whole environmental brief.
GRI / CDP Reporting is one stage of one practice. Most projects need several, and the commitments made at clearance are the ones we build and maintain.
Who we do this for
ESG Advisory & Reporting reads differently by industry.
- 01
River & Water MissionsCore
Multilateral and national mission funding brings E&S safeguard reporting obligations that continue for the life of the programme.
ESG Advisory & Reporting for River & Water Missions - 02
Corporate CampusesCore
BRSR disclosure by the listed parent turns campus energy, water and waste numbers into figures that must be measured and assured.
ESG Advisory & Reporting for Corporate Campuses - 03
Environmental & Social Due DiligenceCore
Funds need portfolio-level E&S management systems and reporting that satisfy their own LPs and development-finance investors.
ESG Advisory & Reporting for Environmental & Social Due Diligence - 04
Data Centres & IT Parks
Operators carry public net-zero and water-positive commitments that require carbon accounting at the campus, then disclosure up the chain.
ESG Advisory & Reporting for Data Centres & IT Parks - 05
Chemical Industry
Pharma and specialty buyers now push supplier ESG data down the chain, so a mid-size chemical unit is disclosing whether or not it is listed.
ESG Advisory & Reporting for Chemical Industry - 06
Industrial & Manufacturing
BRSR obligations on listed customers push supplier ESG and Scope 3 data requests onto unlisted manufacturers in their value chain.
ESG Advisory & Reporting for Industrial & Manufacturing
Trusted by
The organisations this work is done for.
In the press