CER vs CSR: two different obligations, two different laws, and money that cannot be counted twice.
CER is an Environment Clearance condition imposed by the environment authority; CSR is a company law obligation under section 135 of the Companies Act 2013, and expenditure under one generally cannot be claimed under the other.
What it is
The two are confused constantly, and the confusion is expensive. CSR applies to a company that crosses the financial thresholds in section 135 of the Companies Act 2013, requires spending of at least two per cent of average net profits of the three immediately preceding financial years on Schedule VII activities, is governed by a board CSR committee and policy, and is reported to the Ministry of Corporate Affairs. CER applies to a project because its Environment Clearance says so, is fixed by the appraisal committee on a need basis for the project-affected area, and is reported to the environment authority in the clearance compliance report.
KIPL advises proponents that are subject to both (which is common, since a large project is often owned by a company above the CSR thresholds) on how to structure and record the two programmes so each is separately evidenced. The governing constraint is that the Companies (CSR Policy) Rules exclude activities undertaken in pursuance of statutory obligations under any other law from qualifying as CSR, which is why a CER commitment discharged from the CSR budget creates exposure on the company law side rather than efficiency.
What you get
The deliverables, in hand.
- Authority
- Section 135 Companies Act 2013 & CSR Rules · MoEF&CC CER conditions
- Typical timeline
- Advisory in weeks; programmes run on their own cycles
- Applicability determination for CSR and for CER against the client's position
- Comparative obligation note covering trigger, quantum, scope and reporting
- Separated programme design with distinct budgets and records
- Eligibility screening of proposed activities against each regime
- Documentation and evidence protocol for each obligation
- Reporting inputs for the board report and the EC compliance report
Straight answers
CER vs CSR Eligibility: common questions.
01What is the core difference between CER and CSR?
The source of the obligation. CSR arises from company law and attaches to a company because of its size and profitability. CER arises from environmental law and attaches to a project because its Environment Clearance imposes it. One is regulated by the Ministry of Corporate Affairs, the other by the environment authority that granted the clearance.
02Can CER expenditure be claimed as CSR?
Generally no. The Companies (CSR Policy) Rules exclude from CSR any activity undertaken in pursuance of a statutory obligation under any other law in force in India, and CER spend made to satisfy a clearance condition falls squarely within that exclusion. A company that funds its CER commitment out of its CSR budget risks a shortfall against its section 135 obligation.
03Who is covered by CSR?
A company that, in the immediately preceding financial year, has net worth, turnover or net profit above the thresholds specified in section 135 of the Companies Act 2013. Where it applies, the company must spend at least two per cent of the average net profits of the three immediately preceding financial years, constitute a CSR committee where required, and adopt a board-approved policy.
04Who is covered by CER?
Any project whose Environment Clearance carries a CER condition, irrespective of the size or profitability of the company behind it. A project company that has made no profit at all and falls entirely outside section 135 can still carry a substantial CER obligation, because CER is tied to the project and its impacts, not to the company's accounts.
05Where can each be spent?
CSR must be spent on activities within Schedule VII of the Companies Act, with a stated preference for the local area of operations but no strict geographical bar. CER is directed at the area affected by the project, the villages and habitations that carry its impacts, as specified in the clearance condition. CER is therefore geographically tight in a way CSR is not.
06How is each reported?
CSR is reported in the annual report through the prescribed CSR annexure to the board report, in the filing made to the Ministry of Corporate Affairs, and on the company website; unspent amounts must be dealt with under the statutory mechanism for ongoing and non-ongoing projects. CER is reported in the half-yearly compliance report against the Environment Clearance, with expenditure and delivery evidence. Two regulators, two formats, two sets of records.
07Does CSR require impact assessment?
For companies above a specified average CSR obligation, the CSR Rules require impact assessment through an independent agency for projects above a specified outlay that have been completed for a defined minimum period. There is no equivalent general statutory requirement for CER, though appraisal committees and regional offices increasingly expect verification of delivery rather than expenditure statements alone.
08What should a company subject to both actually do?
Plan them as two programmes with separate budgets, separate approval routes and separate evidence files, and screen every proposed activity against the regime it is being funded from before commitment rather than after. Where a genuine local need could be met under either, decide deliberately which obligation it discharges and record that decision. The risk is not in doing good work but in claiming one rupee twice.
Within CSR / CER Advisory
Part of the whole route, the other components.
Primary sources
Check it at source.
This page describes Section 135 Companies Act 2013 & CSR Rules · MoEF&CC CER conditions. The regulation and the filing portal are public, these are the official endpoints, not our summary of them.
Relevant proof
Where this stage has already been delivered.
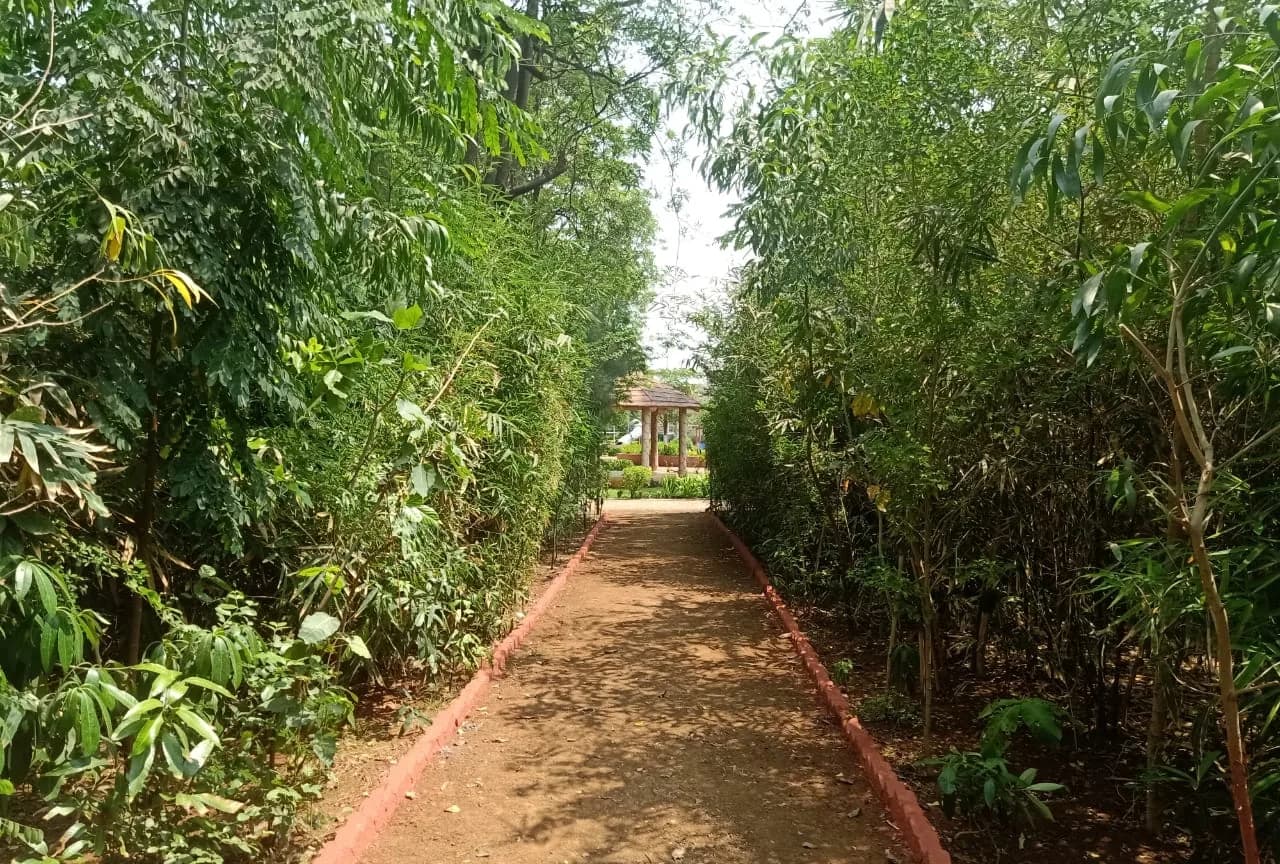
MCGM · Eastern Suburbs, Mumbai
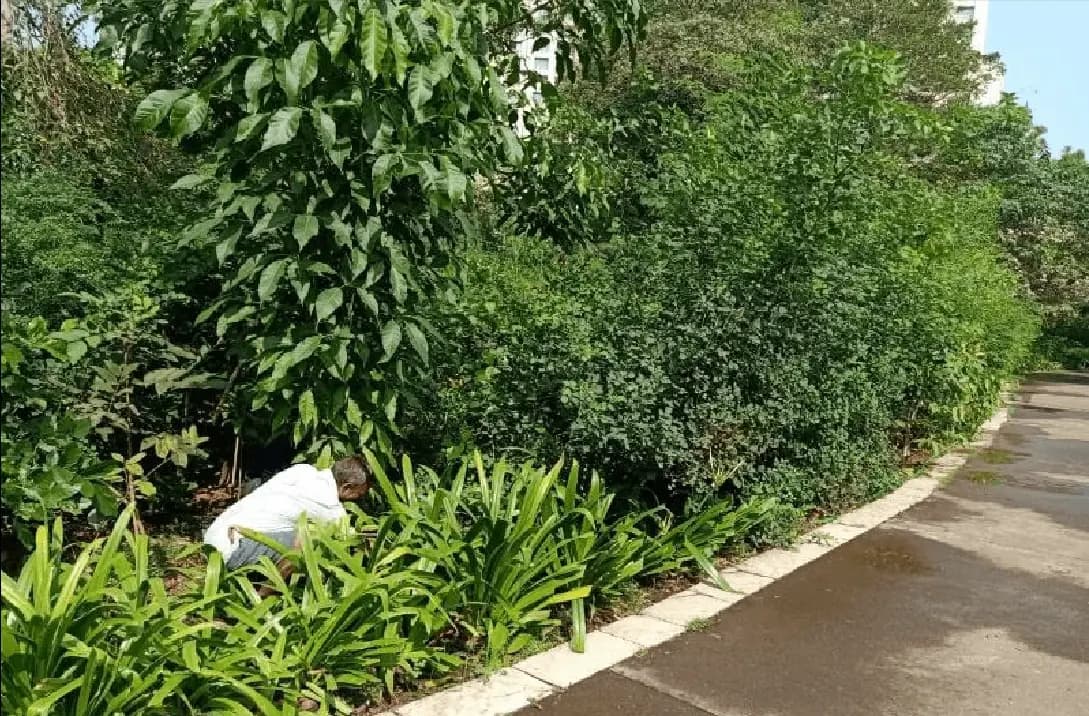
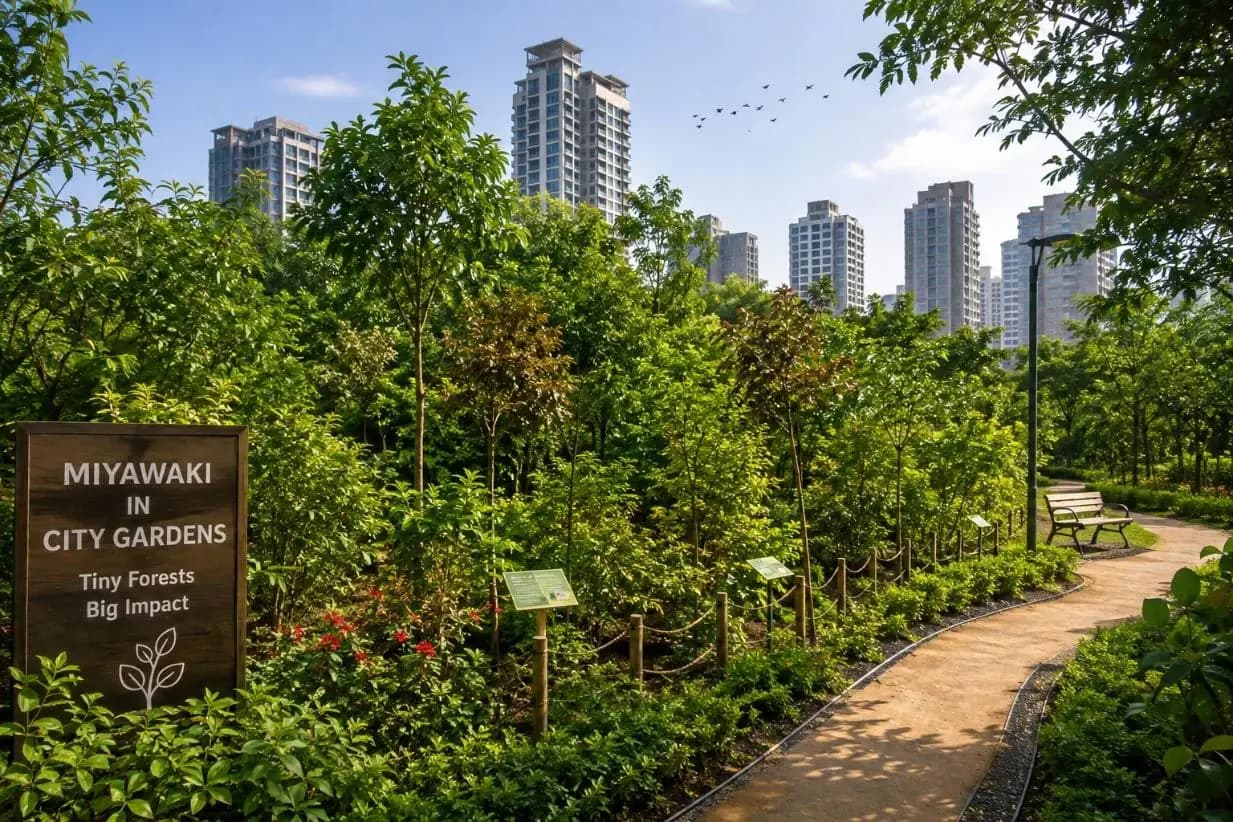
MCGM GARDEN DEVELOPMENT- MIYAWAKI PLANTATION
Miyawaki dense forestation across 27 locations in 7 wards using native species, delivered under the municipal greening programme.
Where we do this
CSR / CER Advisory on the ground.
The authority, the timeline and the local ground differ by city. These pages set out how csr / cer advisory actually runs in each.
- Ahmedabad
- Ambernath
- Andhra Pradesh
- Badlapur
- Bengaluru
- Bhiwandi
- Chennai
- Chhatrapati Sambhajinagar
- Delhi NCR
- Gandhinagar
- Goa
- Gujarat
- Gurugram
- Haryana
- Hyderabad
- Indore
- Jaipur
- Kalyan-Dombivli
- Karnataka
- Kerala
- Kharghar
- Kochi
- Kolhapur
- Kolkata
- Lucknow
- Madhya Pradesh
- Maharashtra
- Mira-Bhayandar
- Mormugao
- Mumbai
- Nagpur
- Nashik
- Navi Mumbai
- New Delhi
- Noida
- Panaji
- Panvel
- Pune
- Punjab
- Rajasthan
- Rajkot
- Solapur
- Surat
- Taloja
- Tamil Nadu
- Telangana
- Thane
- Ulhasnagar
- Uran
- Uttar Pradesh
- Vadodara
- Vasai-Virar
- Visakhapatnam
- West Bengal
Featured projects
Work that carries its own evidence.
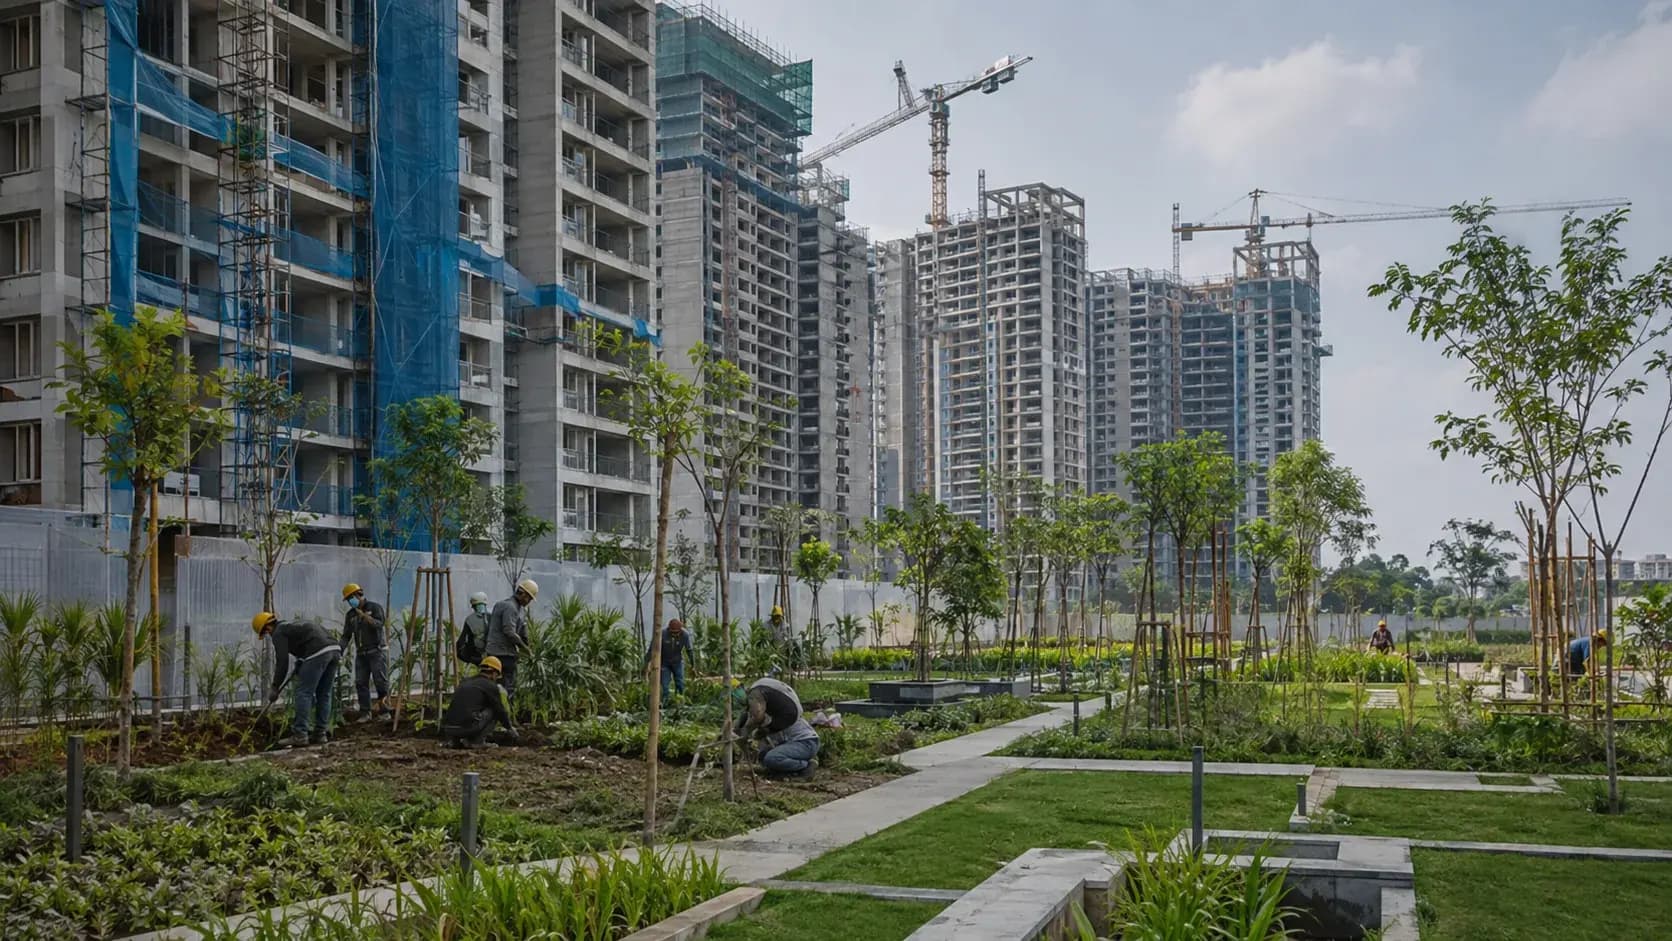
Our expertise
One team across the whole environmental brief.
CER vs CSR Eligibility is one stage of one practice. Most projects need several, and the commitments made at clearance are the ones we build and maintain.
Who we do this for
CSR / CER Advisory reads differently by industry.
- 01
Data Centres & IT ParksCore
Capital-cost-linked CER spend under the 2018 OM is a hard EC condition on projects of this size, delivered inside the 10 km zone of influence.
CSR / CER Advisory for Data Centres & IT Parks - 02
Chemical Industry
CER spend under the 2018 OM is set as a percentage of capital cost and has to land in the 10 km zone of influence, with evidence.
CSR / CER Advisory for Chemical Industry - 03
Distilleries & Ethanol
CER conditions on a new distillery are directed at the surrounding villages that carry the odour and groundwater concern in the public hearing.
CSR / CER Advisory for Distilleries & Ethanol - 04
Sugar Industry
CER commitments made at expansion sit in the same villages that supply the cane, so delivery is visible and locally accounted for.
CSR / CER Advisory for Sugar Industry - 05
Industrial & Manufacturing
Where an expansion carried an EC, the CER commitment is a spend with a location and an evidence trail, distinct from the company's CSR budget.
CSR / CER Advisory for Industrial & Manufacturing - 06
Mining & Minerals
Mining CER obligations are large, local and politically visible, and are the commitments the public hearing record is judged against.
CSR / CER Advisory for Mining & Minerals - 07
Logistics & Ports
Coastal clearances carry CER commitments aimed at fishing and gaothan communities, whose objections shaped the public hearing.
CSR / CER Advisory for Logistics & Ports
Trusted by
The organisations this work is done for.
In the press