CSR / CER Advisory · Sugar Industry
CER and CSR Advisory for Sugar Mills
A CER commitment made when a sugar mill's expansion was cleared has to be spent in the villages around the mill: the same villages that grow the cane, attended the public hearing and will notice whether it happened.
Screening view on your project, with the category and route named. No obligation.
What this means for sugar industry
Corporate Environment Responsibility is a condition of the clearance, not a discretionary donation. Where an expansion carries a CER commitment under the MoEF&CC's office memorandum of 1 May 2018, the amount is tied to the project's capital cost, the activities are those identified around the project site, and the spend is reported in the half-yearly compliance reports with location and evidence. It is distinct from CSR under section 135 of the Companies Act 2013, which is a profit-linked corporate obligation with its own board committee, schedule of permitted activities and annual reporting: a mill can carry both, and mixing the two is a reliable way to satisfy neither. In sugar the CER geography is unusually tight: the mill's impact zone, its cane catchment and its member or supplier base are largely the same villages, which means delivery is visible in a way it is not for a plant on an anonymous industrial estate.
How KIPL runs it
KIPL takes the CER commitment from the clearance letter and turns it into a delivered, evidenced programme: activities selected against what the surrounding villages actually raised at the public hearing rather than a generic list, sited and costed, delivered with local institutions, and documented with location, spend, beneficiary and photographic record in the format the compliance report will consume. Where the mill also has a CSR obligation, we keep the two ledgers separate so a rupee is not reported twice. The failure this avoids is common and quietly damaging: a commitment made at appraisal, no budget line assigned, no owner, and then a half-yearly report that restates the commitment year after year with nothing behind it, in front of an appraisal committee that will read it again when the mill comes back for its next expansion.
- OM 01.05.2018
CER is a clearance condition
The MoEF&CC office memorandum on Corporate Environment Responsibility ties a capital-cost-linked spend to activities around the project site, reported through the EC compliance mechanism.
- s.135
CSR is a different obligation
CSR under the Companies Act 2013 is profit-linked with its own permitted activities and board reporting. Where a mill carries both, the ledgers and the reports have to stay separate.
The impact zone is the cane catchment
The villages in the CER geography supply the cane and were represented at the public hearing, so delivery is locally verified whether or not the regulator visits.
What you receive
Written for sugar industry, not adapted from a template.
- 01CER commitment extracted from the clearance letter with the amount, the activity heads and the geography stated as conditioned
- 02Activity plan mapped against issues raised at the public hearing in the cane-supplying villages
- 03Site-wise costing and implementation schedule with named local institutions or gram panchayat counterparts
- 04Separate CER and CSR ledgers so a single spend is never reported under both regimes
- 05Evidence pack per activity: location coordinates, spend, beneficiaries, photographs and completion record
- 06CER progress section formatted for the half-yearly EC compliance report and for the next appraisal
Questions from sugar industry
What sugar industry ask before appointing us.
Answered against the regulation as it stands, not as a sales pitch. If your situation is not here, ask us directly.
Ask a question →How is CER different from CSR for a sugar mill?
CER arises from the Environment Clearance, is linked to the project's capital cost under the MoEF&CC memorandum of 1 May 2018, is spent around the project site and is reported through the EC compliance reports. CSR arises under section 135 of the Companies Act 2013, is linked to profit, follows the Act's schedule of activities and is reported in the board's annual report. A mill may have both, and they cannot be satisfied with the same rupee.
Where must the CER spend go?
To the area affected by the project, which for a mill is the surrounding villages inside its impact zone. Because those are also the cane-supplying villages, the practical test is whether the local community can point to what was done. Activities chosen from the concerns actually raised at the public hearing (water, school infrastructure, health, sanitation, roads) are both easier to justify at appraisal and more likely to be used.
Can a co-operative mill route CER through its existing village work?
Only where the activity, the location and the spend can be identified separately and tied to the clearance condition. Co-operatives often already do village work through the society, and the risk is that the CER commitment is assumed to be covered by it without any distinct record. The condition is discharged by evidence, so the CER activities need their own line items even if the delivery mechanism is shared.
What evidence does a compliance report need for CER?
Activity, location, amount spent against the amount committed, timing, beneficiaries and photographic proof of what exists on the ground. A narrative that repeats the commitment without figures is what draws queries. Recording the evidence at the time of delivery is far easier than assembling it two years later when the appraisal committee asks.
Our CER commitment is several years old and largely unspent. What now?
State the position accurately in the next compliance report and put a dated completion plan behind it. An acknowledged shortfall with a funded schedule is a defensible position; a report that has claimed progress without evidence is not, and the mill will be asked about it when it files its next expansion. The commitment does not lapse with time.
Who should own CER delivery inside the mill?
A named officer with a budget line, reporting to the same person who owns the EC compliance report, usually the works or administrative head rather than the process team. CER fails when it belongs to everyone, and it is one of the few clearance conditions that requires community engagement rather than plant work, so it needs an owner who is equipped for that.
Stage by stage
How csr / cer advisory actually runs, step by step.
Also for sugar industry
The rest of the environmental brief for this sector.
Primary sources
Verify any of this at the source.
Relevant proof
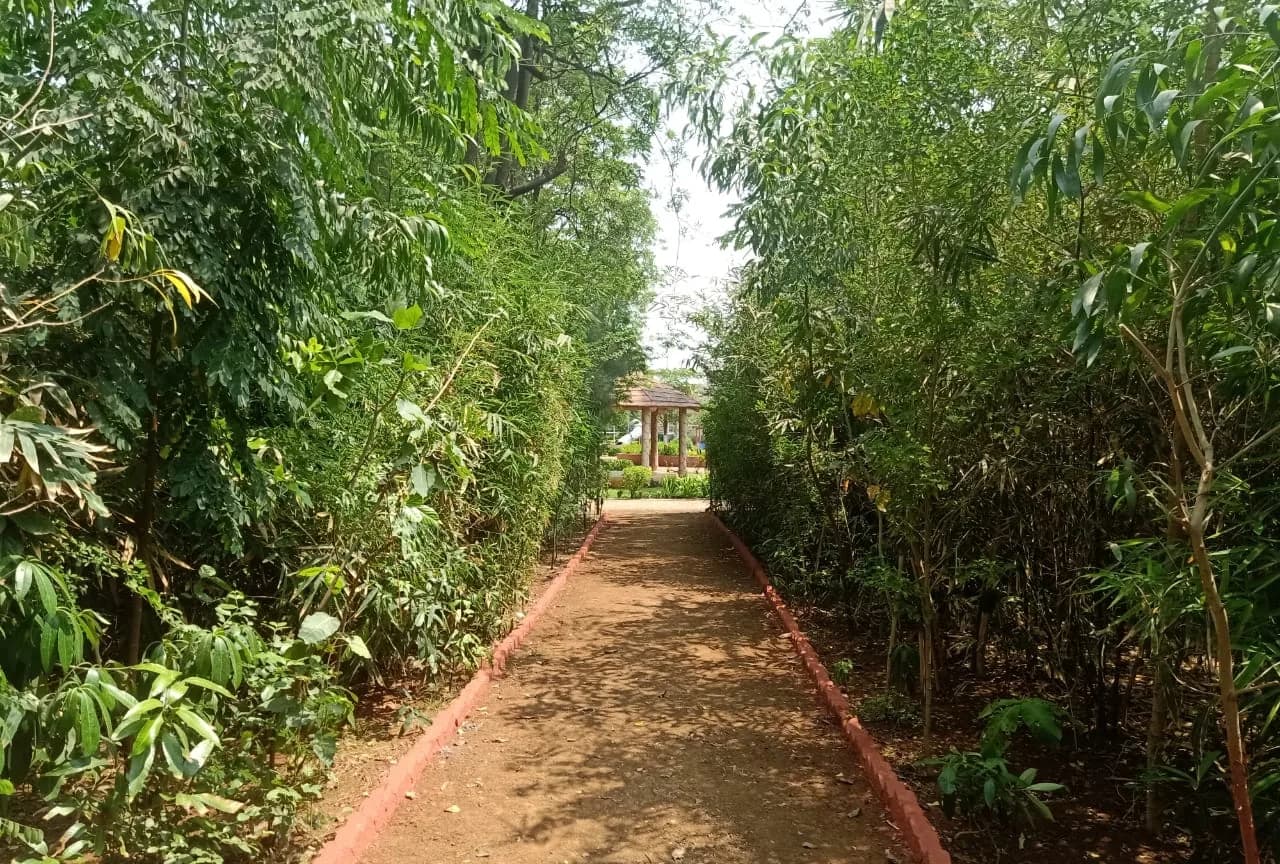
MCGM GARDEN DEVELOPMENT- MIYAWAKI PLANTATION
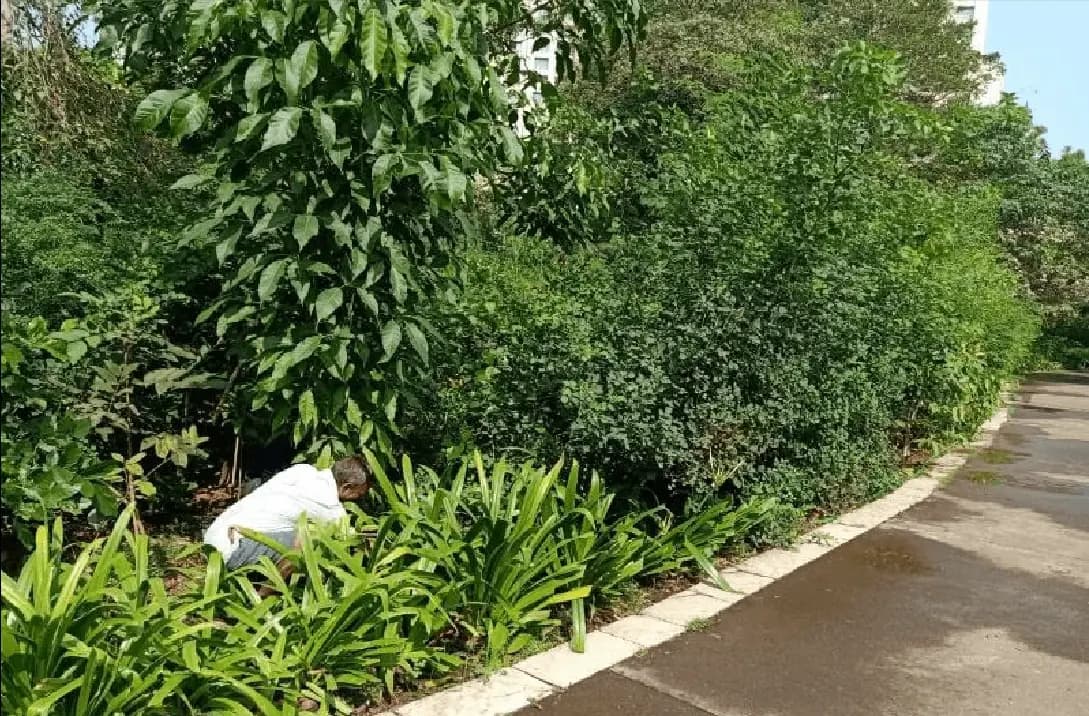
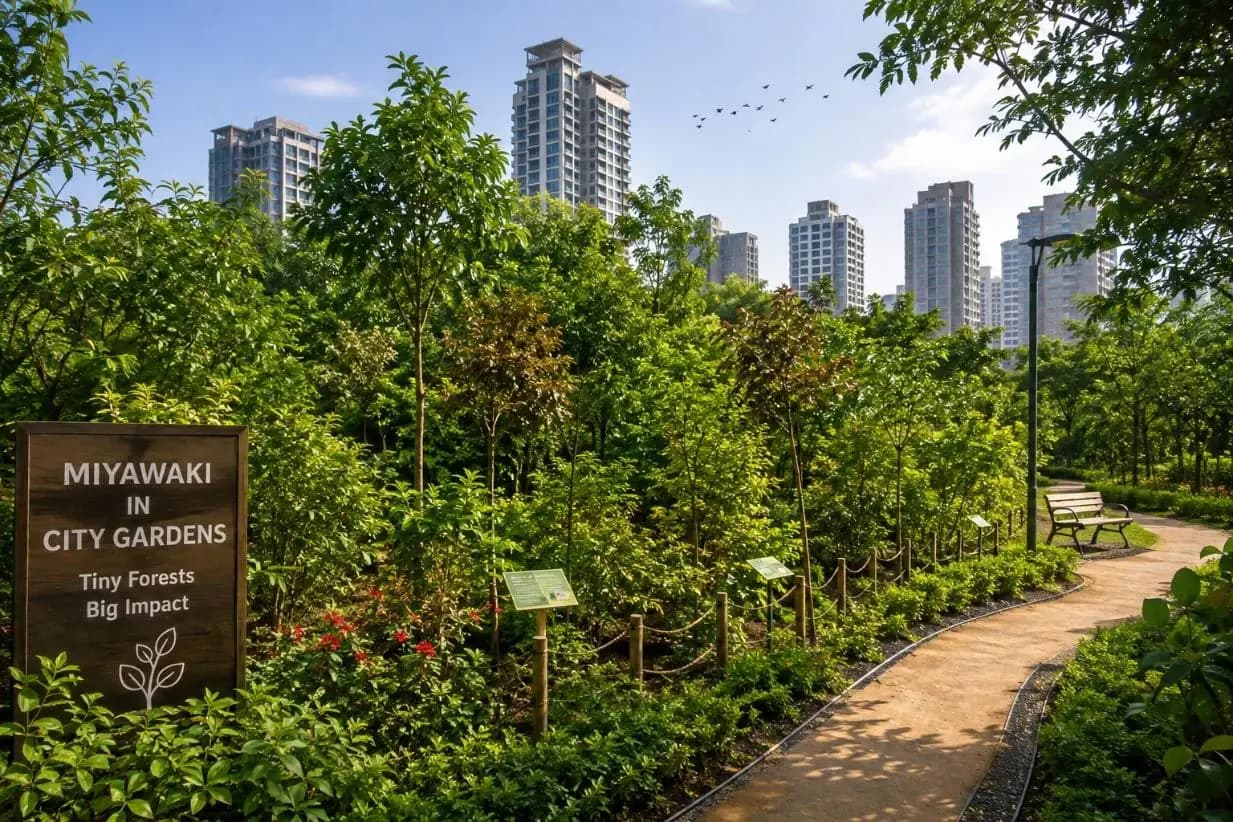
Miyawaki dense forestation across 27 locations in 7 wards using native species, delivered under the municipal greening programme.
- Area
- ~74,000 m²
- Trees
- ≈1,10,000
- CO₂ (est.)
- 2,052 t
Where we do this
CSR / CER Advisory for sugar industry, city by city.
Other sectors
Who else we run csr / cer advisory for.
Next step
Tell us the project, and we will tell you the category and the route.
Screening is the cheapest stage to get right and the most expensive to get wrong. We will say plainly what csr / cer advisory your sugar industry project needs, and what it does not.
Start the conversation