Cost control and MIS: knowing where a project's money and schedule actually stand.
Cost control keeps a running, reconciled picture of budget, commitment and expenditure so that an overrun is visible while it can still be managed, not discovered at final account.
What it is
The discipline is a monthly cycle: measured work certified, variations valued and approved or contested, commitments tracked against the sanctioned budget, cash flow forecast against the programme, and the forecast cost at completion revised on the evidence. Alongside it sits schedule reporting: planned versus achieved progress, critical path status, and the causes of slippage, including extension of time claims and their entitlement.
KIPL produces MIS that is decision-grade rather than decorative: one reconciled set of numbers, a clear statement of what has changed since last month and why, and the specific decisions the owner needs to take. Variations and claims are logged when they arise, with their contractual basis noted, because a change identified at the time is a manageable commercial item, while the same change surfacing at final account is a dispute.
What you get
The deliverables, in hand.
- Authority
- Conditions of contract · owner's delegation of authority
- Typical timeline
- Monthly cycle through the project, closing at final account
- Cost control register: budget, committed, certified and forecast at completion
- Variation and change order log with contractual basis and valuation
- Extension of time and claim register with entitlement assessment
- Cash flow forecast and S-curve against the programme
- Monthly MIS report with progress, cost, risk and decisions required
- Final account reconciliation at completion
Straight answers
Cost Control & MIS Reporting: common questions.
01What is the difference between committed and incurred cost?
Committed cost is the value the owner is contractually bound to, including orders placed and variations approved, whether or not work has been done. Incurred cost is the value of work actually executed and certified. Tracking only invoices received hides commitments that have already been made, which is how projects appear on budget until they suddenly are not.
02Why does forecast cost at completion matter more than expenditure to date?
Because expenditure to date is history and the forecast is the only number a decision can be taken on. A revised forecast at completion, built from certified work, approved variations, known claims and remaining scope, tells the owner whether the sanctioned budget will hold, while there is still scope to act.
03How are variations controlled?
By logging each change when it arises, recording the instruction or the event that caused it, establishing its contractual basis, valuing it against contract rates or agreed rates, and obtaining approval before the work proceeds wherever that is practicable. Uninstructed and unvalued changes accumulate quietly and are settled expensively at final account.
04What should a monthly MIS report contain?
Physical progress against programme, cost position across budget, committed, certified and forecast, the variation and claim registers, cash flow against forecast, quality and safety summary, the current risk position, and an explicit list of decisions the owner needs to take. Anything else is context; those are the contents.
05Who owns the numbers?
The owner. The consultant compiles, reconciles and reports, and the contractor submits its claims and measurements, but the cost control register is the owner's record of its own commitment. Where the owner's finance system and the project register diverge, reconciling them is part of the job rather than an accounting inconvenience.
06How are extension of time claims assessed?
Against the contract: what event occurred, whether it is a compensable or excusable delay under the conditions, what its effect on the critical path was, and what relief the contract provides. Assessing entitlement contemporaneously, with the programme evidence available, is far more reliable than reconstructing causation months later.
07Does cost control conflict with the supervision role?
They are complementary and should share one record. Certification of work done under supervision is the input to the cost position; when they are kept in separate systems, the certified value and the reported cost drift apart and neither is trusted. Running them off a single set of measurements is what keeps the MIS credible.
Within Project Management Consultancy
Part of the whole route, the other components.
Relevant proof
Where this stage has already been delivered.
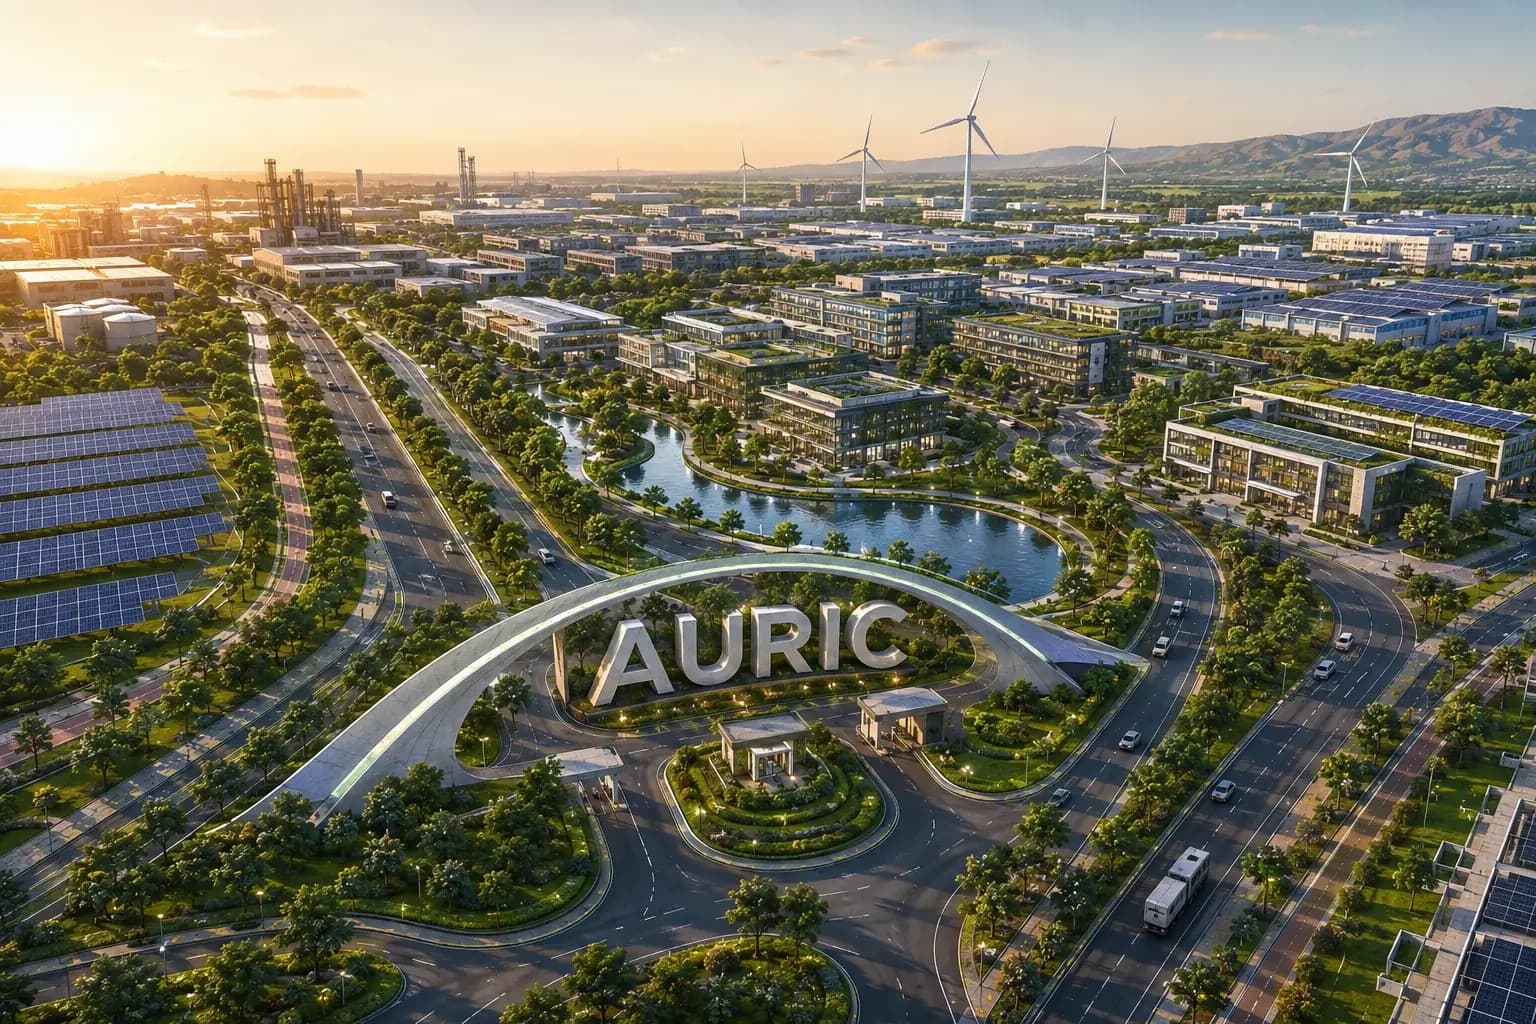
MIDC / AURIC · Shendra & Bidkin, Chhatrapati Sambhajinagar
SHENDRA AND BIDKIN INDUSTRIAL AREA, AURANGABAD
Environmental compliance audits, Consent to Establish and green certification support across two industrial nodes of the Delhi-Mumbai Industrial Corridor.
Where we do this
Project Management Consultancy on the ground.
The authority, the timeline and the local ground differ by city. These pages set out how project management consultancy actually runs in each.
Featured projects
Work that carries its own evidence.
Our expertise
One team across the whole environmental brief.
Cost Control & MIS Reporting is one stage of one practice. Most projects need several, and the commitments made at clearance are the ones we build and maintain.
Who we do this for
Project Management Consultancy reads differently by industry.
- 01
River & Water MissionsCore
In-situ and ex-situ treatment programmes run across many drains and contractors, needing procurement, supervision and MIS as one discipline.
Project Management Consultancy for River & Water Missions - 02
Municipal Corporations
Corporations need vendor prequalification, techno-commercial bid evaluation and supervision to make an environmental tender defensible.
Project Management Consultancy for Municipal Corporations - 03
Industrial Corridors & MIDC
Corridor authorities procure environmental infrastructure through competitive tender and need prequalification, bid evaluation and supervision to hold it together.
Project Management Consultancy for Industrial Corridors & MIDC
Trusted by
The organisations this work is done for.
In the press